
Block and Flow Reinsurance for Annuity Liabilities: A Strategic Guide
For life and annuity carriers, the choice between block and flow reinsurance is a critical capital decision. American Reinsurance offers both block and flow reinsurance solutions specifically designed for annuity liabilities. This guide explains how these two distinct structures function, the strategic implications of each, and how a specialized partner can help you optimize your balance sheet. We will explore the mechanics of liability transfer, the benefits of ongoing capacity, and the regulatory considerations that drive these transactions in 2026.
Introduction to Annuity Reinsurance
Annuity liabilities are long-duration obligations that require significant capital reserves. For insurers, managing these reserves is a primary driver of capital efficiency. Reinsurance is a risk transfer mechanism that allows insurers to cede a portion of their liability to a reinsurer. This process frees up capital that can be used for new business or strategic investments. The two primary methods for transferring annuity risk are block reinsurance and flow reinsurance. Each method serves a different strategic purpose and has distinct accounting and regulatory implications.
Block reinsurance involves the transfer of an existing portfolio of policies, often referred to as an in-force book. This is a one-time transaction that provides immediate relief to the balance sheet. Flow reinsurance, on the other hand, involves the transfer of risk on new policies as they are issued. This is an ongoing arrangement that provides continuous capacity for growth. Understanding the differences between these two approaches is essential for any carrier looking to optimize its capital structure. American Reinsurance specializes in both, providing tailored solutions that align with your specific business goals.
Athene Block Reinsurance
Block reinsurance is a strategic tool for releasing capital from legacy liabilities. It is often used when a carrier is undergoing corporate restructuring, seeking to optimize its capital position, or pursuing an M&A strategy. The transaction involves the sale of a closed block of policies to a reinsurer. This transfer removes the associated reserves from the carrier's balance sheet, providing immediate surplus relief. The reinsurer assumes the risk of the transferred policies, including mortality, longevity, and investment risks.
Strategic Drivers for Block Transactions
Carriers typically pursue block reinsurance for several strategic reasons. First, it provides immediate capital relief, which can improve regulatory ratios and ratings stability. Second, it allows the carrier to focus on its core business without the drag of legacy liabilities. Third, it can be used to fund growth initiatives or return capital to shareholders. The key to a successful block transaction is structuring it to meet the specific accounting, tax, and asset strategies of the carrier. A well-structured block deal can enhance financial flexibility while maintaining transparency and regulatory integrity.
Structuring and Execution
The execution of a block reinsurance transaction requires careful planning and coordination. It involves actuarial analysis, legal structuring, and regulatory approval. The transaction must be designed to fit the carrier's specific needs, whether that is a full runoff, a partial transfer, or a transfer of an acquired portfolio. The reinsurer must have the financial strength and expertise to assume the risk of the transferred block. American Reinsurance brings deep expertise in structuring these complex transactions, ensuring that they are tailored to the client's objectives and regulatory environment.
Athene Flow Reinsurance
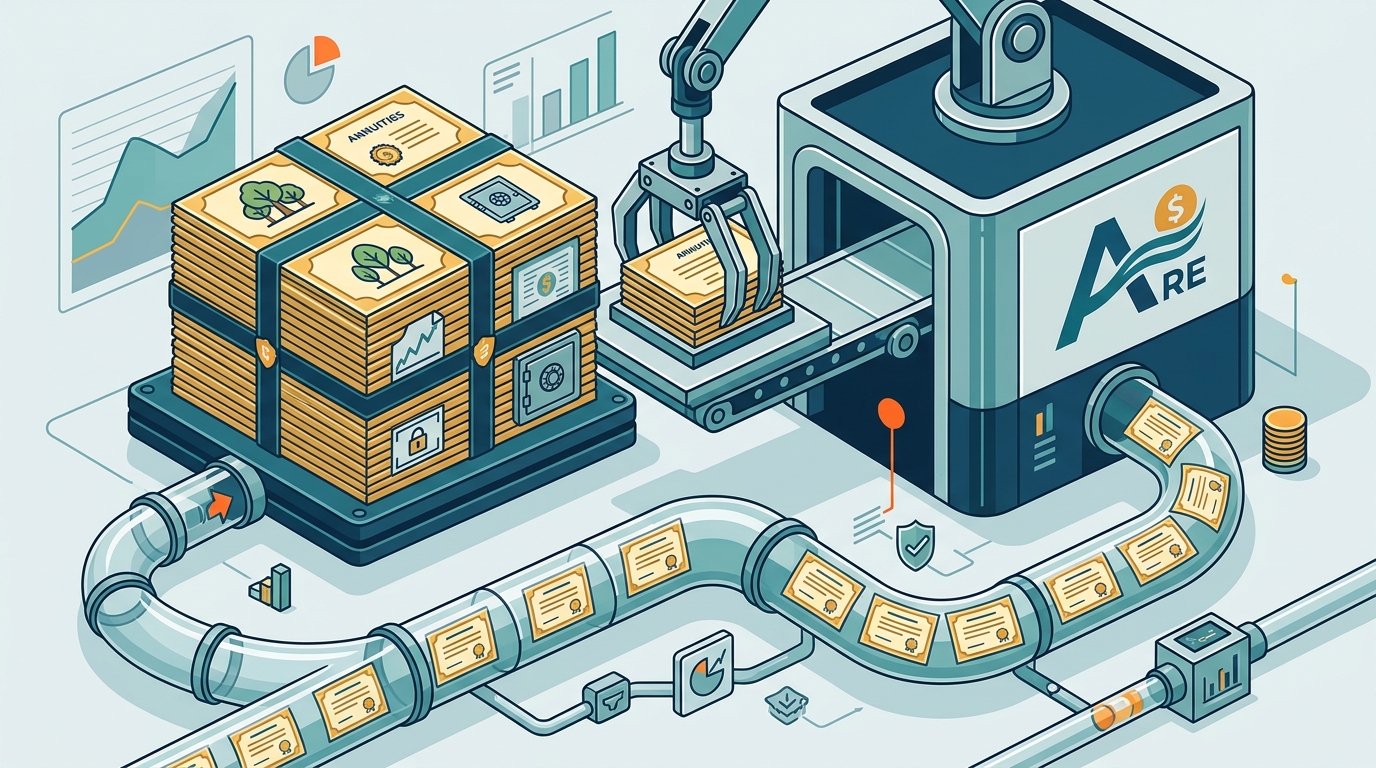
Flow reinsurance is a scalable capital solution for ongoing growth. It provides consistent capacity for new business production, allowing carriers to grow confidently over time. Unlike block reinsurance, which is a one-time event, flow reinsurance is an ongoing arrangement. It involves the transfer of risk on new policies as they are issued. This provides the carrier with the ability to manage reserve growth while maintaining balance sheet strength. Flow reinsurance is particularly useful for carriers that are actively issuing new annuity products and need to manage the associated capital requirements.
Benefits of Ongoing Capacity
The primary benefit of flow reinsurance is the provision of ongoing capacity for new business. This allows carriers to grow their book of business without being constrained by capital limits. It also provides a mechanism for managing reserve growth, which can be a significant challenge for carriers with large annuity portfolios. Flow reinsurance can be structured to support a variety of products, including fixed annuities, indexed annuities, and participating annuities. The structure is designed to integrate seamlessly with new issuance, allowing the carrier to grow confidently over time.
Integration with New Issuance
Integrating flow reinsurance with new issuance requires careful coordination between the carrier's underwriting, actuarial, and finance teams. The reinsurance structure must be designed to fit the carrier's specific product mix and risk appetite. It must also be aligned with the carrier's capital planning and strategic goals. A well-designed flow reinsurance program can provide significant value to the carrier by enabling growth while managing capital efficiently. American Reinsurance offers flow reinsurance programs that are tailored to the specific needs of each client, ensuring that they are aligned with the carrier's business model.
Block vs. Flow: A Strategic Comparison
Choosing between block and flow reinsurance depends on the carrier's strategic objectives. Block reinsurance is best suited for carriers that need immediate capital relief from legacy liabilities. Flow reinsurance is best suited for carriers that need ongoing capacity for new business growth. The following table summarizes the key differences between the two approaches.
| Feature | Block Reinsurance | Flow Reinsurance |
|---|---|---|
| Transaction Type | One-time transfer of existing portfolio | Ongoing transfer of new policies |
| Capital Impact | Immediate surplus relief | Continuous capacity for growth |
| Strategic Purpose | Restructuring, M&A, capital optimization | New business growth, reserve management |
| Duration | Finite (runoff or closed block) | Indefinite (ongoing program) |
| Complexity | High (legal, actuarial, regulatory) | Medium (integration with issuance) |
It is important to note that these two approaches are not mutually exclusive. Many carriers use a combination of block and flow reinsurance to achieve their strategic goals. For example, a carrier might use block reinsurance to release capital from a legacy portfolio and then use flow reinsurance to support the growth of its new business. This hybrid approach can provide a comprehensive solution for managing annuity liabilities. American Reinsurance can help you design a reinsurance strategy that combines both block and flow elements to meet your specific needs.
Key Takeaways
- Block reinsurance provides immediate capital relief by transferring existing annuity liabilities.
- Flow reinsurance offers ongoing capacity for new business growth and reserve management.
- The choice between block and flow depends on the carrier's strategic objectives and capital needs.
- A hybrid approach combining both block and flow can be an effective strategy for comprehensive risk management.
- Regulatory and accounting considerations are critical in structuring both block and flow transactions.
- Partnering with a specialized reinsurer like American Reinsurance ensures that your reinsurance strategy is tailored to your specific goals.
Frequently Asked Questions
What is the main difference between block and flow reinsurance?
Block reinsurance involves the transfer of an existing portfolio of policies, while flow reinsurance involves the transfer of risk on new policies as they are issued. Block is a one-time transaction, while flow is an ongoing arrangement.
Can a carrier use both block and flow reinsurance?
Yes, many carriers use a combination of both. Block reinsurance can be used to release capital from legacy liabilities, while flow reinsurance can be used to support the growth of new business.
How does block reinsurance impact a carrier's balance sheet?
Block reinsurance removes the associated reserves from the carrier's balance sheet, providing immediate surplus relief. This can improve regulatory ratios and ratings stability.
What types of annuities are eligible for flow reinsurance?
Flow reinsurance can support a variety of annuity products, including fixed, indexed, and participating annuities. The specific products eligible depend on the structure of the reinsurance program.
How long does a block reinsurance transaction take to complete?
The timeline for a block reinsurance transaction varies depending on the complexity of the portfolio and the regulatory environment. It can take several months to complete, involving actuarial analysis, legal structuring, and regulatory approval.
What are the regulatory considerations for block reinsurance?
Block reinsurance transactions must comply with applicable regulatory requirements, including those related to capital adequacy, risk transfer, and accounting. The transaction must be structured to meet the specific regulatory environment of the carrier.
Conclusion
Selecting the right reinsurance partner is a critical decision for any life and annuity carrier. The choice between block and flow reinsurance depends on your specific strategic objectives and capital needs. A specialized partner can help you navigate the complexities of these transactions and design a strategy that aligns with your business goals. American Reinsurance offers both block and flow reinsurance solutions, providing the expertise and financial strength to support your growth. To discuss your reinsurance needs, today.