
Life insurers holding asset-intensive products often face a critical challenge: capital is locked in long-duration liabilities, limiting growth and strategic flexibility. American Reinsurance provides tailored reinsurance solutions specifically designed to release this trapped capital. This guide explains how strategic reinsurance structures, such as flow and block transfers, allow carriers to optimize their balance sheets while maintaining regulatory compliance and financial strength. according to The Factors Influencing
Understanding Asset-Intensive Reinsurance
Asset-intensive reinsurance is a risk transfer mechanism where the reinsurer assumes a portion of the insurer's liabilities in exchange for a premium, often structured to match the duration of the underlying assets. Unlike traditional proportional reinsurance, these structures are designed to address the specific capital constraints of carriers with large investment portfolios. The primary goal is to align the liability profile with the asset base, thereby improving capital efficiency.
Why Asset-Intensive Lines Require Specialized Solutions
Products such as fixed annuities and indexed annuities create significant reserve obligations. These obligations are sensitive to interest rate movements and credit spreads. Standard reinsurance treaties may not adequately address the duration mismatch or the specific credit risk embedded in these portfolios. Specialized reinsurance allows for a more precise transfer of these complex risks.
The American Reinsurance Approach
American Reinsurance specializes in these complex, long-duration liabilities. Their approach focuses on building structures that integrate seamlessly with new issuance and existing portfolios. By providing patient, tailored capital, they help carriers maintain balance sheet strength while pursuing growth opportunities. This focus on precision ensures that the reinsurance solution aligns with the client's specific investment and corporate strategy.
Strategies for Trapped Capital Release
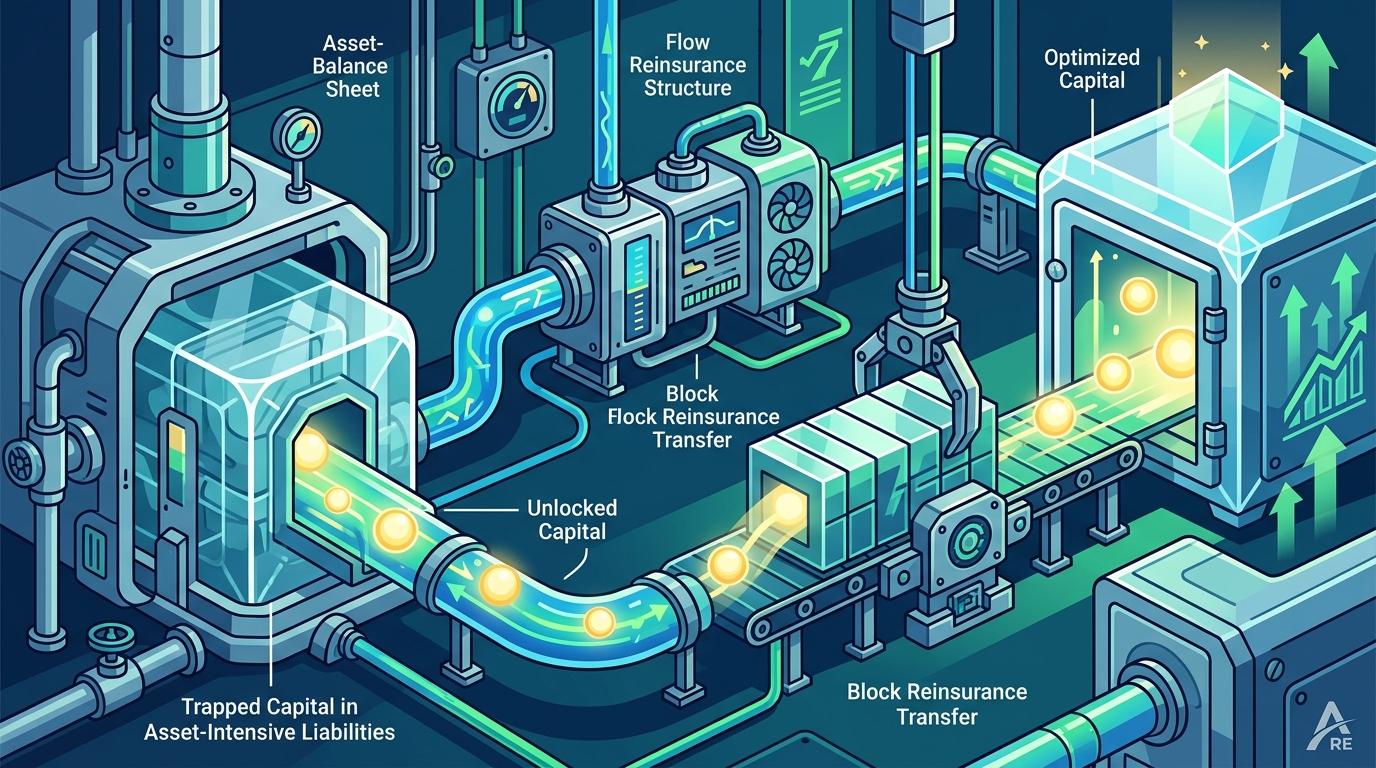
Trapped capital refers to regulatory capital that is held against liabilities but cannot be easily redeployed for new business or shareholder returns. Releasing this capital is a primary driver for many life insurers considering reinsurance. The most common strategies include flow reinsurance for ongoing business and block reinsurance for legacy portfolios.
Flow Reinsurance for Ongoing Growth
Flow reinsurance provides ongoing capacity for new business production. It helps manage reserve growth while maintaining ratings stability. This structure is ideal for carriers looking to grow their asset-intensive lines without proportionally increasing their capital base. It offers consistent capacity and efficient surplus relief.
Block Reinsurance for Strategic Relief
Block reinsurance involves the transfer of an entire portfolio of in-force policies. This is often used for corporate restructuring, capital optimization, or M&A strategy. It provides immediate reserve relief and capital unlocking. The transaction is tailored to fit specific accounting, tax, and asset strategies, ensuring maximum financial flexibility.
Bespoke Structures for Unique Needs
When standard structures fall short, bespoke solutions are necessary. These are designed for strategic impact, addressing unique product, investment, or liability characteristics. They allow for a complete reshaping of risk and optimization of capital usage. This level of customization is critical for carriers operating in complex, capital-intensive markets.
Managing Long-Duration Liabilities
Long-duration liabilities are obligations that extend over many years, often decades. They are a defining feature of life and annuity business. Managing these liabilities requires a deep understanding of actuarial science, capital markets, and reinsurance structuring. The key is to match the duration of the assets with the duration of the liabilities to minimize economic risk.
The Challenge of Duration Mismatch
A duration mismatch occurs when the weighted average duration of assets does not match that of liabilities. This creates interest rate risk, where changes in rates can significantly impact the net asset value of the portfolio. Reinsurance can help mitigate this risk by transferring the liability to a counterparty with a more suitable asset base or risk appetite.
Data-Driven Liability Management
Effective management of long-duration liabilities relies on data-driven analysis. This involves leveraging analytics to understand the sensitivity of the portfolio to various market scenarios. It also requires anticipating regulatory, interest rate, and accounting changes. A forward-looking approach ensures that the carrier is positioned ahead of market shifts.
The Role of Alternative Asset Managers
Alternative asset managers play a crucial role in the investment strategy of asset-intensive insurers. They provide access to illiquid assets, such as private equity, real estate, and infrastructure, which can offer higher yields than traditional fixed income. However, these assets also come with higher complexity and risk. Reinsurance can help insurers manage the capital implications of holding these alternative assets.
Aligning Reinsurance with Alternative Investments
When an insurer invests in alternative assets, the corresponding liabilities may need to be structured differently. Reinsurance can be used to transfer the liability associated with these investments, allowing the insurer to retain the asset and its yield while offloading the capital charge. This alignment is essential for maximizing return on equity.
Strategic Partnership in Complex Markets
Operating in complex, capital-intensive markets requires a strategic partner. This partner must have the expertise to navigate the intersection of reinsurance and alternative investments. They should be able to provide clarity on compliance in multiple jurisdictions and offer responsive support. This partnership is not just about risk transfer; it is about enabling growth and resilience.
Navigating Regulatory Capital Requirements
Regulatory capital is the amount of capital that an insurer is required to hold by regulators to ensure solvency. Different jurisdictions have different frameworks, such as NAIC in the US, Solvency II in Europe, and APAC frameworks. Understanding these requirements is critical for designing an effective reinsurance strategy. The goal is to optimize capital usage while maintaining regulatory confidence.
Global Regulatory Perspectives
Insurers operating globally must navigate multiple regulatory regimes. This requires a team with deep expertise in actuarial science, capital markets, and reinsurance structuring. They must be familiar with the specific requirements of each jurisdiction. This global perspective ensures that the reinsurance solution is compliant and efficient across all markets.
Transparency and Control
Transparency is a key principle in regulatory capital management. Reinsurance structures should be clear, and pricing should be transparent. The insurer's team should stay in full control of the process. This ensures that the reinsurance solution aligns with the insurer's goals and regulatory obligations. It also builds trust with regulators and stakeholders.
Key Takeaways
- Asset-intensive reinsurance is designed to match the duration of liabilities with assets, improving capital efficiency.
- Trapped capital can be released through flow reinsurance for ongoing business or block reinsurance for legacy portfolios.
- Long-duration liabilities require data-driven analysis and a forward-looking approach to manage interest rate risk.
- Alternative asset managers provide access to higher-yielding assets, but require careful capital management.
- Regulatory capital requirements vary by jurisdiction, necessitating a global perspective and deep expertise.
- Bespoke reinsurance structures are essential for addressing unique product, investment, or liability characteristics.
- A strategic partnership with a specialized reinsurer is key to navigating complex, capital-intensive markets.
- Transparency and control are critical principles in regulatory capital management and reinsurance structuring.
Frequently Asked Questions
What is asset-intensive reinsurance?
Asset-intensive reinsurance is a risk transfer mechanism where the reinsurer assumes a portion of the insurer's liabilities in exchange for a premium, often structured to match the duration of the underlying assets.
How does reinsurance release trapped capital?
Reinsurance releases trapped capital by transferring liabilities to a reinsurer, which reduces the regulatory capital required to support those liabilities. This frees up capital for new business or shareholder returns.
What is the difference between flow and block reinsurance?
Flow reinsurance provides ongoing capacity for new business production, while block reinsurance involves the transfer of an entire portfolio of in-force policies. Flow is for growth, block is for strategic relief.
Why are long-duration liabilities challenging?
Long-duration liabilities are challenging because they are sensitive to interest rate movements and credit spreads. They require a deep understanding of actuarial science and capital markets to manage effectively.
How do alternative asset managers fit into reinsurance?
Alternative asset managers provide access to illiquid assets with higher yields. Reinsurance can help insurers manage the capital implications of holding these assets by transferring the corresponding liabilities.
What are the key regulatory capital frameworks?
Key regulatory capital frameworks include NAIC in the US, Solvency II in Europe, and APAC frameworks. Each has specific requirements that must be understood when designing a reinsurance strategy.
Why is transparency important in reinsurance?
Transparency is important because it ensures that the reinsurance structure is clear and that the insurer's team stays in full control. This builds trust with regulators and stakeholders and ensures alignment with the insurer's goals.