
Statutory reserve credit allows annuity carriers to reduce their reported liabilities on the balance sheet by transferring risk to a reinsurer. This reduction directly lowers the capital required to support those liabilities, thereby freeing up surplus for new business or strategic initiatives. By leveraging this mechanism, insurers can optimize their risk-based capital ratios and maintain ratings stability while continuing to grow their in-force portfolios. For additional details, review the About us 8211 American.
The Mechanics of Balance Sheet Relief
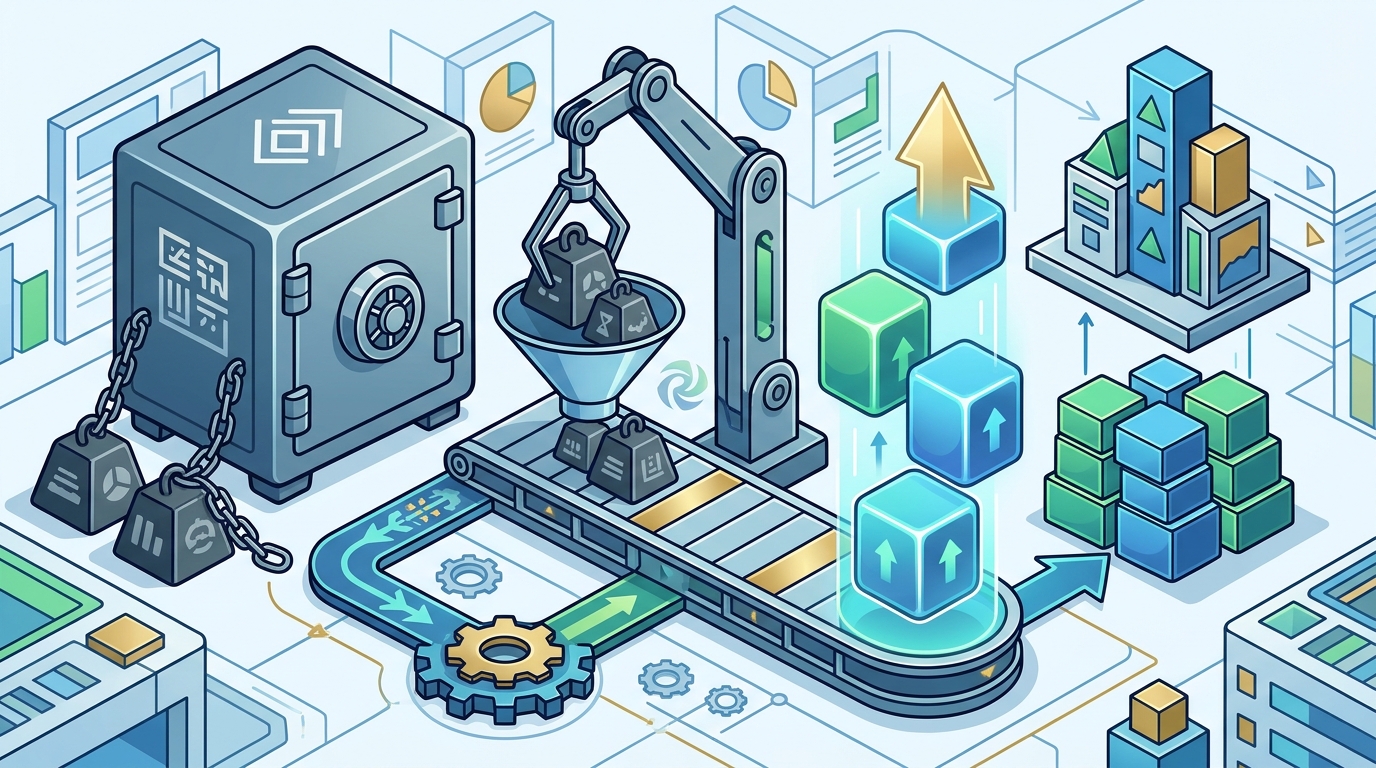
Statutory reserve credit is the accounting recognition that a portion of an insurer's liabilities has been transferred to a reinsurer. When a ceding company enters a reinsurance treaty or block transaction, the ceded reserves are deducted from the total statutory reserves. This deduction reduces the denominator in capital adequacy calculations, effectively increasing the available surplus. For annuity carriers, this is critical because long-duration liabilities require significant capital buffers under regulatory frameworks.
The process begins with the ceding company reporting its gross reserves. The reinsurer then assumes a specific percentage or the entire liability. The ceding company reports the net reserves, which are the gross reserves minus the ceded amount. This net figure is what regulators and rating agencies use to assess financial strength. The implication is that capital efficiency improves without necessarily reducing the insurer's ability to pay claims, as the reinsurer now shares the financial burden.
Regulatory Frameworks and Capital Ratios
Regulatory capital requirements are driven by risk-based capital (RBC) rules, which mandate that insurers hold a certain amount of capital relative to their risk profile. Annuity liabilities, particularly those with long durations and complex guarantees, carry high risk charges. By ceding these liabilities, the insurer reduces its risk-based capital charge. This allows the company to maintain or improve its RBC ratio, which is a key metric for regulatory compliance and market confidence.
For example, a carrier with a large block of fixed annuities may face high interest rate risk charges. By transferring a portion of this block to a reinsurer, the carrier reduces its exposure to interest rate fluctuations. This reduction in risk charge directly translates to lower required capital. The result is a stronger balance sheet that can support further growth or absorb unexpected losses without breaching regulatory minimums.
Strategic Implications for Annuity Carriers
Moreover, capital relief can improve an insurer's ability to compete in the market. With a stronger balance sheet, a carrier can offer more competitive pricing or terms to policyholders. This can lead to increased market share and long-term profitability. The key is to structure the reinsurance transaction in a way that aligns with the carrier's long-term strategic goals, ensuring that the capital relief is sustainable and beneficial.
Structuring Effective Reinsurance Transactions
Effective reinsurance transactions require careful structuring to maximize capital relief while minimizing costs. The choice between flow reinsurance and block reinsurance depends on the carrier's specific needs. Flow reinsurance provides ongoing capacity for new business, while block reinsurance releases capital from legacy liabilities. Both approaches can provide statutory reserve credit, but they serve different strategic purposes.
When structuring a transaction, carriers must consider the reinsurer's financial strength, the terms of the treaty, and the regulatory implications. A strong reinsurer with a solid capital base can offer better terms and pricing. Additionally, the transaction must be structured to ensure that the reserve credit is recognized by regulators. This requires clear documentation and compliance with statutory accounting principles. The goal is to create a partnership that delivers long-term value and stability.
Key Takeaways
- Statutory reserve credit reduces reported liabilities, directly lowering required capital.
- This mechanism improves risk-based capital ratios, enhancing regulatory compliance.
- Capital relief enables strategic growth, including new product launches and M&A activities.
- Both flow and block reinsurance can provide reserve credit, depending on the carrier's goals.
- Choosing a financially strong reinsurer is critical for sustainable capital relief.
- Proper structuring ensures regulatory recognition of the reserve credit.
Frequently Asked Questions
What is statutory reserve credit?
Statutory reserve credit is the accounting reduction in an insurer's liabilities resulting from the transfer of risk to a reinsurer.
How does reserve credit affect capital ratios?
By reducing liabilities, reserve credit lowers the capital required to support those liabilities, thereby improving capital ratios.
Can all annuity carriers use reserve credit?
Yes, any carrier that cedes risk to a qualified reinsurer can benefit from statutory reserve credit, subject to regulatory approval.
What is the difference between flow and block reinsurance?
Flow reinsurance covers new business, while block reinsurance transfers existing in-force portfolios. Both can provide reserve credit.
How long does it take to implement a reinsurance transaction?
The timeline varies, but it typically involves several months of negotiation, due diligence, and regulatory approval.
Conclusion
Statutory reserve credit is a powerful tool for annuity carriers seeking to optimize their capital structure. By transferring risk to a strategic partner, insurers can free up capital, improve regulatory ratios, and pursue long-term growth. American Reinsurance specializes in providing tailored reinsurance solutions that deliver this capital relief, ensuring that our partners can grow with confidence. To explore how we can support your capital objectives, .