
Top Capital-Backed Reinsurance Structures for Life Insurers in 2026
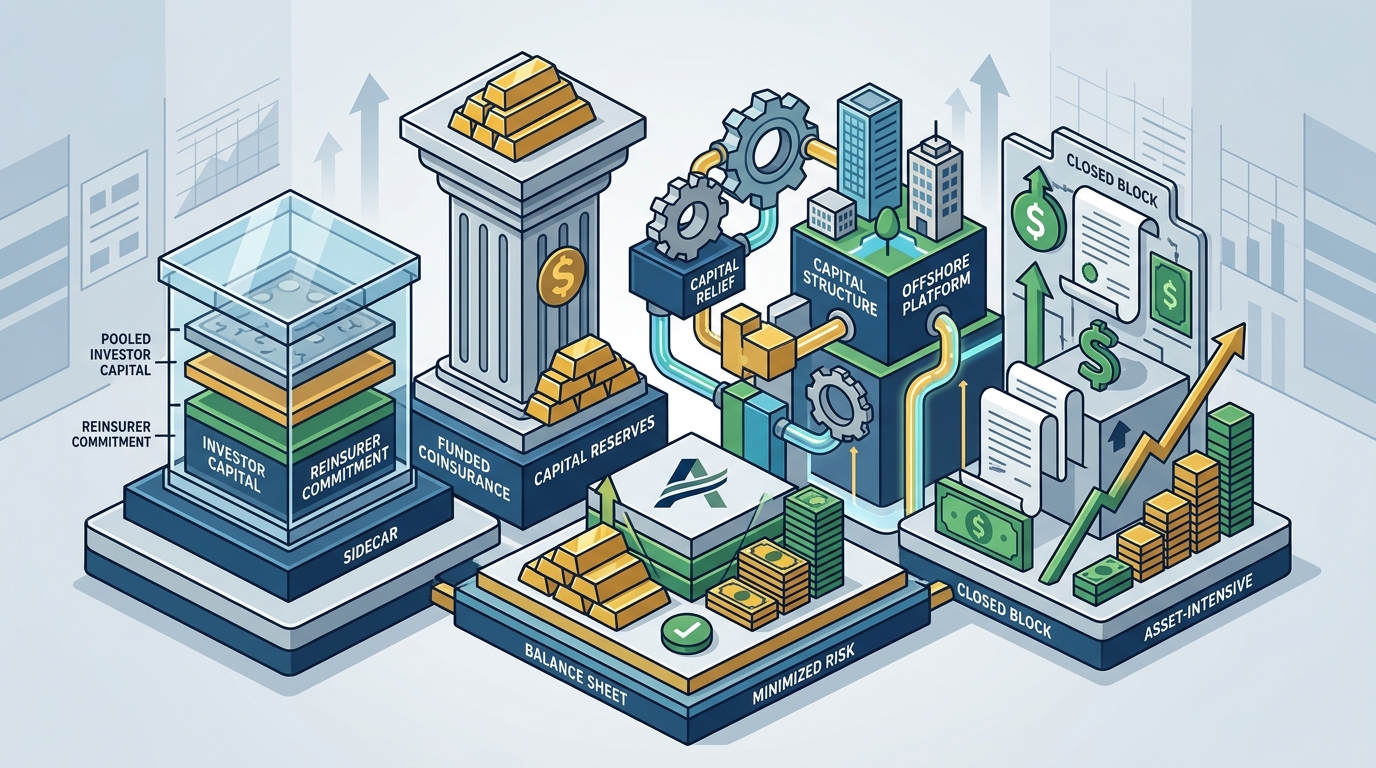
Capital-backed reinsurance structures are financial arrangements where a reinsurer provides upfront capital to support an insurer's balance sheet. These structures allow life insurers to optimize risk, enhance solvency ratios, and support growth in asset-intensive lines. This guide examines the top five structures, including sidecars, funded coinsurance, and offshore platforms, to help you build a resilient capital strategy. according to Accounting for Reinsurance
Reinsurance Sidecars
Reinsurance sidecars are specialized vehicles that allow investors to share in the underwriting results of a specific book of business. These structures are particularly effective for life insurers seeking to offload risk while retaining a portion of the upside. By using a sidecar, an insurer can transfer a defined layer of risk to a dedicated pool of capital. This approach provides a flexible mechanism for managing volatility in long-duration liabilities. For additional details, review the Terms of services 8211.
Investor Alignment and Capital Efficiency
Sidecars align the interests of the insurer and the investors by sharing both profits and losses. This alignment encourages disciplined underwriting and risk management. For life carriers, sidecars can be used to support new business issuance or to manage existing in-force portfolios. The capital provided by the sidecar is typically ring-fenced, ensuring that the insurer's core balance sheet remains protected from adverse outcomes in the transferred book.
Strategic Applications for Life Insurers
Life insurers often use sidecars to support growth in asset-intensive products such as fixed and indexed annuities. These vehicles allow carriers to scale their operations without proportionally increasing their own capital requirements. The structure can be tailored to specific product lines or geographic regions, providing a high degree of customization. This flexibility makes sidecars a valuable tool for insurers navigating complex regulatory environments.
Funded Coinsurance
Balance Sheet Relief and Regulatory Capital
By transferring assets and liabilities to a funded coinsurance partner, insurers can achieve significant balance sheet relief. This relief is particularly valuable for carriers operating under strict regulatory capital requirements. The structure allows insurers to free up capital that can be redeployed for new business or strategic initiatives. The regulatory treatment of funded coinsurance can vary by jurisdiction, so it is essential to work with a partner who understands the local regulatory landscape.
Long-Term Partnership Dynamics
Funded coinsurance is often structured as a long-term partnership, reflecting the long-duration nature of life insurance liabilities. This long-term focus ensures that the reinsurer is committed to the success of the ceded book. The partnership model fosters transparency and collaboration, allowing both parties to work together to optimize outcomes. This approach is particularly well-suited for insurers seeking to build a sustainable capital strategy over time.
Collateralized Structures
Collateralized structures are reinsurance arrangements where the reinsurer provides collateral to secure its obligations to the ceding company. This collateral can take the form of cash, letters of credit, or other financial instruments. The primary benefit of collateralized structures is the reduction of counterparty risk. By securing the reinsurer's obligations, the ceding company can be confident that it will be able to recover its ceded reserves in the event of a reinsurer default.
Counterparty Risk Mitigation
Counterparty risk is a significant concern for life insurers, particularly when ceding large blocks of business. Collateralized structures provide a robust mechanism for mitigating this risk. The collateral is typically held in a trust or escrow account, ensuring that it is available to the ceding company if needed. This security provides peace of mind to the ceding company and its regulators, supporting the approval of the reinsurance transaction.
Flexibility in Collateral Forms
Longevity and Mortality Risk Transfer
Longevity and mortality risk transfer is the process of transferring the risk of changes in life expectancy to a reinsurer. This type of risk transfer is particularly relevant for life insurers with significant annuity portfolios. By transferring longevity risk, insurers can protect themselves from the financial impact of people living longer than expected. Similarly, mortality risk transfer allows insurers to manage the risk of higher-than-expected death rates.
Managing Annuity Portfolio Risk
Annuity portfolios are exposed to significant longevity risk, as the duration of the liabilities is directly linked to the life expectancy of the annuitants. By transferring this risk to a reinsurer, insurers can reduce the volatility of their cash flows and improve their capital position. This risk transfer can be structured as a pure reinsurance transaction or as part of a broader capital-backed solution. The reinsurer assumes the risk in exchange for a premium, providing the insurer with a predictable income stream.
Strategic Capital Optimization
Longevity and mortality risk transfer is a key component of a strategic capital optimization plan. By offloading these risks, insurers can free up capital that can be used to support new business or meet regulatory requirements. This approach allows insurers to grow their annuity business without proportionally increasing their capital base. The structure can be tailored to specific risk factors, providing a high degree of precision in risk management.
Offshore Affiliate Platforms
Offshore affiliate platforms are reinsurance structures where an insurer establishes an affiliate in a jurisdiction with favorable regulatory and tax treatment. These platforms allow insurers to cede business to their own affiliate, providing a high degree of control and flexibility. The offshore jurisdiction often offers a stable regulatory environment and efficient tax treatment, making it an attractive option for life insurers. This structure is particularly well-suited for insurers seeking to optimize their global capital strategy.
Regulatory and Tax Advantages
Offshore jurisdictions such as the Cayman Islands offer a stable and well-regulated environment for reinsurance operations. The regulatory framework in these jurisdictions is designed to support the efficient operation of reinsurance businesses. Additionally, the tax treatment of reinsurance income in offshore jurisdictions can be favorable, providing a significant advantage for insurers. These advantages make offshore affiliate platforms a popular choice for life insurers seeking to optimize their capital structure.
Control and Flexibility
By using an offshore affiliate, insurers retain a high degree of control over the reinsurance transaction. This control allows for a high degree of flexibility in structuring the transaction to meet the insurer's specific needs. The affiliate can be tailored to the insurer's business model, providing a seamless integration with the parent company's operations. This level of control and flexibility is a key benefit of offshore affiliate platforms, making them a valuable tool for strategic capital management.
Structure Comparison Table
| Structure | Primary Benefit | Capital Efficiency | Best For |
|---|---|---|---|
| Reinsurance Sidecars | Investor alignment and risk sharing | High | New business growth and volatility management |
| Funded Coinsurance | Immediate balance sheet relief | Very High | Regulatory capital optimization |
| Collateralized Structures | Counterparty risk mitigation | Medium | Large block transfers and security needs |
| Longevity/Mortality Transfer | Protection against life expectancy changes | High | Annuity portfolio risk management |
| Offshore Affiliate Platforms | Regulatory and tax advantages | Very High | Global capital strategy and control |
Key Takeaways
- Capital-backed reinsurance structures provide immediate balance sheet relief and improve solvency ratios.
- Reinsurance sidecars offer a flexible mechanism for sharing underwriting results with investors.
- Funded coinsurance is highly capital-efficient, allowing insurers to optimize their regulatory capital.
- Collateralized structures mitigate counterparty risk by securing the reinsurer's obligations.
- Longevity and mortality risk transfer protects insurers from changes in life expectancy.
- Offshore affiliate platforms provide regulatory and tax advantages in favorable jurisdictions.
- The choice of structure depends on the insurer's specific capital, risk, and strategic objectives.
- Working with a strategic partner ensures that the structure is tailored to the insurer's needs.
Frequently Asked Questions
What is the primary benefit of a reinsurance sidecar?
The primary benefit of a reinsurance sidecar is the alignment of interests between the insurer and investors. This alignment encourages disciplined underwriting and risk management, while providing a flexible mechanism for managing volatility in long-duration liabilities.
How does funded coinsurance improve capital efficiency?
Funded coinsurance improves capital efficiency by providing immediate balance sheet relief. The transfer of assets to the reinsurer frees up capital that can be redeployed for new business or strategic initiatives, optimizing the insurer's regulatory capital ratios.
What is the role of collateral in reinsurance structures?
Collateral in reinsurance structures serves to mitigate counterparty risk. By securing the reinsurer's obligations, the ceding company can be confident that it will be able to recover its ceded reserves in the event of a reinsurer default.
Why is longevity risk transfer important for life insurers?
Longevity risk transfer is important for life insurers because it protects them from the financial impact of people living longer than expected. This risk transfer is particularly relevant for insurers with significant annuity portfolios, where the duration of the liabilities is directly linked to life expectancy.
What are the advantages of offshore affiliate platforms?
Offshore affiliate platforms offer regulatory and tax advantages in favorable jurisdictions. These platforms allow insurers to cede business to their own affiliate, providing a high degree of control and flexibility in structuring the transaction.
How do I choose the right capital-backed reinsurance structure?
Choosing the right structure depends on your specific capital, risk, and strategic objectives. It is essential to work with a strategic partner who understands your business and can tailor the structure to meet your needs.
What is the role of a strategic partner in reinsurance?
A strategic partner in reinsurance provides tailored, capital-backed solutions that help insurers grow with confidence. They combine financial strength, regulatory expertise, and a deep understanding of the insurer's business to design a bespoke reinsurance program.
Conclusion
Selecting the right capital-backed reinsurance structure is a critical decision for life insurers seeking to optimize their balance sheet and support growth. By understanding the distinct benefits of sidecars, funded coinsurance, and offshore platforms, you can build a resilient capital strategy. American Reinsurance specializes in these complex, long-duration liabilities, delivering patient, tailored capital that aligns with your business model. To plan your visit, to discuss a capital-efficient, custom-fit solution for your business. according to Accounting for Reinsurance