
Unlocking Trapped Capital: Longevity Reinsurance for Annuity Carriers
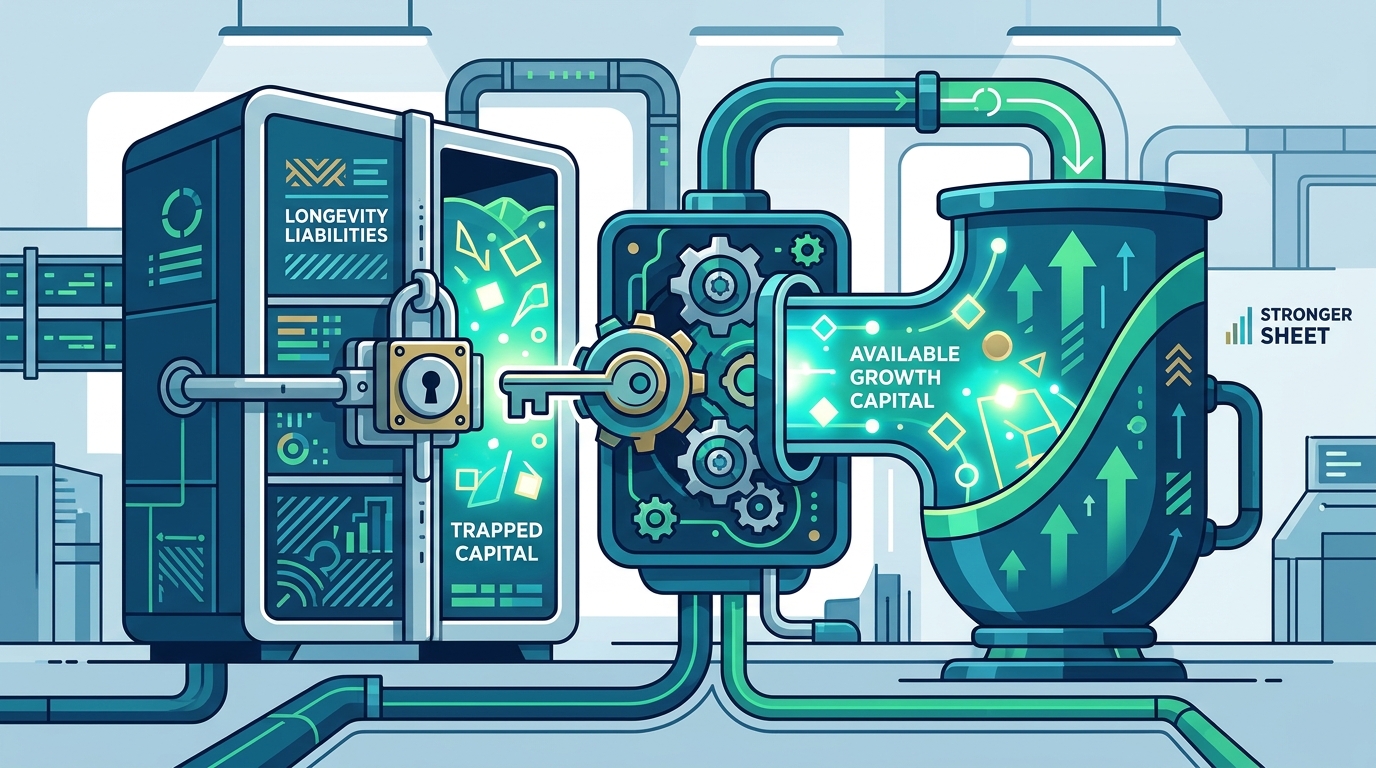
Longevity reinsurance is a risk transfer mechanism that allows annuity carriers to offload the risk of policyholders living longer than expected. By transferring this liability, insurers can release capital trapped in long-duration reserves, improving balance sheet strength and enabling growth in other lines of business. This strategic tool is essential for carriers managing complex, asset-intensive portfolios.
The Mechanics of Longevity Risk Transfer
Longevity risk is the financial exposure arising from the uncertainty of how long annuitants will live. When carriers issue fixed or indexed annuities, they assume the obligation to pay benefits for the life of the policyholder. If mortality rates improve faster than projected, the carrier's liabilities extend, tying up capital that could otherwise be deployed for new business or shareholder returns.
Longevity reinsurance is a contract where a reinsurer assumes a portion or all of this mortality risk. In exchange for a premium, the reinsurer pays the carrier if actual longevity exceeds a predetermined threshold. This structure converts an uncertain, long-tail liability into a known, manageable cost. For carriers, this transforms a potential capital drain into a source of financial flexibility.
The primary benefit is immediate capital relief. By transferring the longevity tail, carriers can reduce their risk-based capital (RBC) charges. This freed capital can be used to support new product issuance, meet regulatory requirements, or return value to shareholders. The key is structuring the deal to match the carrier's specific risk appetite and capital objectives.
Identifying Trapped Capital in Annuity Blocks
Trapped capital is not just a theoretical concept; it is a measurable constraint on growth. Carriers often hold excess capital against in-force annuity blocks because regulatory frameworks require them to reserve for worst-case longevity scenarios. This capital sits idle, earning a return that may not compensate for the opportunity cost of not deploying it elsewhere.
For example, a carrier with a large block of single-premium immediate annuities (SPIAs) may find that a significant portion of its surplus is allocated to longevity risk. If the carrier wants to expand into variable annuities or other asset-intensive lines, this trapped capital becomes a barrier. Longevity reinsurance allows the carrier to monetize this risk, effectively selling the longevity tail to a specialized reinsurer.
Identifying the right block for transfer is critical. Carriers should analyze their portfolio to determine which segments have the highest longevity exposure relative to their capital base. This analysis helps in negotiating favorable terms with reinsurers. The goal is to target the most capital-intensive liabilities for transfer, maximizing the capital efficiency gain.
Structuring the Deal: Flow vs. Block
Carriers have two primary options for longevity reinsurance: flow reinsurance and block reinsurance. Flow reinsurance covers new business issued over a period, while block reinsurance covers an existing portfolio of in-force policies. Each structure serves different strategic goals and has distinct implications for capital and accounting.
Flow reinsurance is ideal for carriers looking to support ongoing growth. By attaching a longevity reinsurance treaty to new business, carriers can maintain a consistent capital position as they scale. This approach provides predictable capital relief and supports ratings stability. It is particularly useful for carriers issuing large volumes of new annuities, as it prevents reserve growth from eroding surplus.
Block reinsurance, on the other hand, is a strategic tool for unlocking capital from legacy liabilities. It is often used in corporate restructuring, M&A, or capital optimization scenarios. A block deal transfers the entire longevity risk of a closed block, providing a one-time capital release. This can be a powerful lever for carriers looking to reposition their balance sheet or fund a strategic initiative. The choice between flow and block depends on the carrier's immediate capital needs and long-term strategy.
Regulatory and Accounting Considerations
Longevity reinsurance transactions are subject to strict regulatory and accounting standards. Carriers must ensure that the reinsurance contract meets the criteria for risk transfer under applicable accounting rules, such as ASC 944 in the US or IFRS 17 internationally. Failure to meet these criteria can result in the transaction being treated as a deposit, which does not provide the desired capital relief.
Regulatory approval is also a key consideration. In many jurisdictions, ceding a block of business requires regulatory consent. Carriers should engage with regulators early in the process to ensure transparency and alignment. This proactive approach can expedite approval and demonstrate the carrier's commitment to sound risk management. Regulatory expertise is crucial in navigating these complexities, ensuring that the transaction is structured in a compliant and efficient manner.
Accounting treatment also impacts the income statement and balance sheet. A properly structured longevity reinsurance deal can improve key performance indicators, such as return on equity (ROE) and capital ratios. Carriers should work with their actuaries and accountants to model the financial impact of the transaction, ensuring that it delivers the intended benefits without introducing unexpected accounting complexities.
Partnering for Precision and Long-Term Alignment
Choosing the right reinsurance partner is as important as structuring the deal. Carriers need a partner with deep expertise in longevity risk, strong financial strength, and a commitment to long-term alignment. A reputable reinsurer will bring data-driven insights and transparent pricing, helping the carrier make informed decisions.
American Reinsurance specializes in providing strategic reinsurance solutions for life and annuity carriers. We focus on asset-intensive and capital-intensive business, offering tailored structures that align with each client's capital objectives and regulatory environment. Our team combines actuarial, regulatory, and structuring insights to design bespoke reinsurance programs. We don't rely on templates; we build solutions around your specific goals.
By partnering with a specialist like American Reinsurance, carriers can navigate the complexities of longevity reinsurance with confidence. We provide the expertise and financial strength to support your growth, ensuring that your capital is deployed where it can generate the most value. Our long-term focus ensures that we are invested in your success, not just in closing a deal.
Key Takeaways
- Longevity reinsurance is a powerful tool for unlocking capital trapped in annuity blocks by transferring mortality risk.
- Carriers should analyze their portfolio to identify the most capital-intensive liabilities for transfer, maximizing capital efficiency.
- Flow reinsurance supports ongoing growth, while block reinsurance provides one-time capital relief from legacy liabilities.
- Regulatory and accounting compliance is critical; ensure the deal meets risk transfer criteria to achieve desired capital relief.
- Partnering with a specialist reinsurer with deep longevity expertise and strong financial strength is essential for successful execution.
- Long-term alignment with a reinsurance partner ensures sustainable capital support and strategic value creation.
Frequently Asked Questions
What is longevity reinsurance?
Longevity reinsurance is a risk transfer mechanism where a reinsurer assumes the risk of policyholders living longer than expected, in exchange for a premium.
How does longevity reinsurance unlock trapped capital?
By transferring the longevity tail, carriers reduce their risk-based capital charges, releasing capital that was previously held against uncertain liabilities.
What is the difference between flow and block longevity reinsurance?
Flow reinsurance covers new business issued over a period, while block reinsurance covers an existing portfolio of in-force policies.
Is longevity reinsurance suitable for all annuity carriers?
It is most beneficial for carriers with significant longevity exposure and capital constraints, particularly those managing asset-intensive or long-duration liabilities.
How long does it take to structure a longevity reinsurance deal?
The timeline varies depending on the complexity of the deal and regulatory requirements, but it typically takes several months to negotiate and execute.
What role does regulatory approval play in longevity reinsurance?
Regulatory approval is often required for block reinsurance transactions, ensuring that the transfer is in the best interest of policyholders and the market.
Next Steps for Annuity Carriers
Unlocking trapped capital through longevity reinsurance requires a strategic approach and the right partner. Carriers should begin by assessing their portfolio's longevity exposure and capital constraints. This analysis will help identify the most suitable reinsurance structure and potential partners.
American Reinsurance is committed to helping insurers navigate these complexities. We provide tailored, capital-backed solutions that empower insurers to grow with confidence. To discuss how longevity reinsurance can support your capital objectives, . We are ready to work with you to design a solution that aligns with your business goals and regulatory environment.