
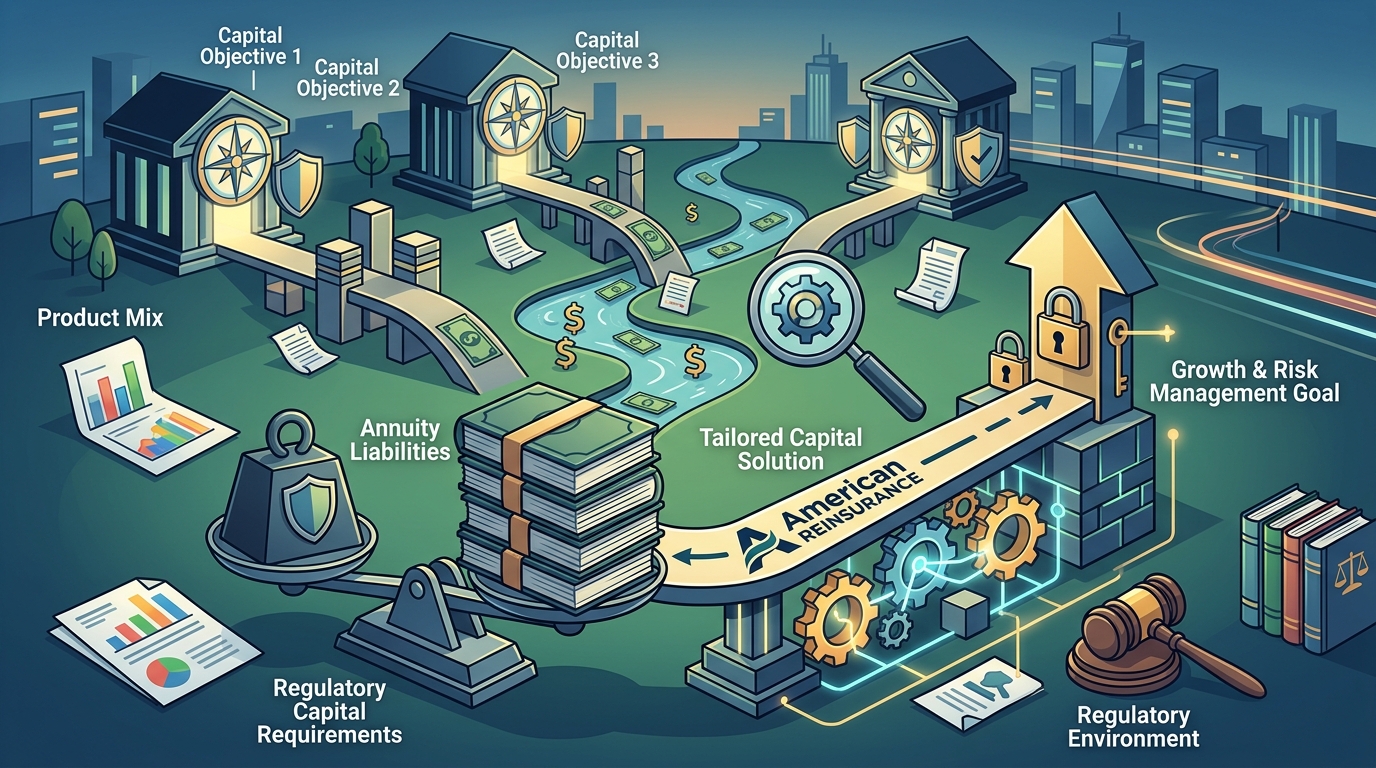
Choosing the right reinsurer for annuity liability capital relief depends on your specific capital objectives, regulatory environment, and product mix. American Reinsurance specializes in tailored, capital-backed solutions for life and annuity carriers, focusing on complex, long-duration liabilities. This guide covers the key structures, evaluation criteria, and strategic considerations for selecting a reinsurance partner that aligns with your growth and risk management goals.
Capital Relief Structures
Capital relief in the annuity sector is not a one-size-fits-all solution. The structure of the reinsurance transaction must align with the insurer's balance sheet dynamics and strategic goals. Flow reinsurance is a structure that provides ongoing capacity for new business, helping carriers manage reserve growth while maintaining balance sheet strength. This approach is ideal for insurers looking to scale their new issuance without compromising ratings stability.
Flow Reinsurance for New Business
Flow reinsurance programs are designed to integrate seamlessly with new product issuance. They support fixed and indexed annuities, participating reinsurance treaties (PRT), and similar products. By transferring a portion of the new business risk, insurers can achieve efficient surplus relief and liability transfer. This allows for consistent capacity for new business production, enabling growth in asset-intensive lines of business.
Block Reinsurance for In-Force Portfolios
Block reinsurance is a transaction that releases capital from legacy liabilities. It is often driven by corporate restructuring, capital optimization, or M&A strategy. Block transactions are tailored to closed blocks, runoff, or acquired portfolios. They provide reserve relief and capital unlocking, enhancing financial flexibility while maintaining transparency and regulatory integrity. The structure is customized to fit accounting, tax, and asset strategies.
Bespoke Solutions for Complex Liabilities
When standard structures fall short, bespoke reinsurance is a custom-built solution that addresses unique product, investment, or liability characteristics. This approach uses reinsurance to reshape risk and optimize capital usage. It is particularly useful for asset-intensive business and cross-border regulatory design. Bespoke solutions offer fully flexible reinsurance structures designed for strategic impact, ensuring that the reinsurance program aligns with the insurer's investment and corporate strategy.
Evaluation Criteria for Reinsurers
Selecting the best reinsurer requires a rigorous evaluation of their capabilities, financial strength, and alignment with your business model. The following criteria are critical when assessing potential partners for annuity liability capital relief.
Financial Strength and Capital Base
A reinsurer's financial strength is the foundation of any reinsurance transaction. A robust capital base allows for better terms and pricing. Insurers should evaluate the reinsurer's capital adequacy, rating agency assessments, and track record of delivering on commitments. American Reinsurance emphasizes financial strength as a core component of its value proposition, ensuring that partners can rely on their capital support.
Structuring Expertise and Precision
The ability to design complex, tailored structures is a key differentiator. Reinsurers should demonstrate deep expertise in actuarial science, capital markets, and reinsurance structuring. They should build solutions from first principles, leveraging analytics rather than templates. Precision in pricing and structuring ensures that the reinsurance program delivers the intended capital relief without introducing unnecessary risk.
Regulatory Expertise and Global Perspective
Reinsurance transactions are subject to regulatory scrutiny in multiple jurisdictions. A strong reinsurer should have a global perspective, familiar with regulatory regimes across key markets, including NAIC, Solvency II, and APAC frameworks. This expertise brings clarity to compliance and ensures that the transaction is structured to meet regulatory requirements in all relevant jurisdictions.
Regulatory Considerations
Regulatory compliance is a critical aspect of reinsurance transactions. The structure of the transaction must be designed to meet the requirements of the relevant regulatory bodies. This includes ensuring that the reinsurance arrangement is recognized for capital relief purposes and that it complies with local and international regulations.
NAIC and Solvency II Frameworks
In the United States, the NAIC framework governs reinsurance transactions. Insurers must ensure that their reinsurance arrangements meet the NAIC's requirements for capital relief. In Europe, Solvency II is the primary regulatory framework. Reinsurers with expertise in both frameworks can help insurers navigate the complexities of cross-border reinsurance transactions.
APAC Regulatory Regimes
For insurers operating in the Asia-Pacific region, understanding the local regulatory regimes is essential. Reinsurers with a global perspective can provide guidance on the specific requirements of APAC markets. This ensures that the reinsurance transaction is structured to meet local regulatory requirements and that the insurer can achieve the desired capital relief.
Strategic Alignment and Partnership
The best reinsurance partner is one that aligns with your strategic goals and values. This includes a commitment to long-term partnership, transparency, and integrity. The reinsurer should work as an extension of your team, aligning their workstreams with yours from day one.
Long-Term Partnership
Reinsurance is not just a short-term relief mechanism. It is a long-term partnership that requires trust and alignment. A strong reinsurer should be committed to building sustainable partnerships, not just one-time deals. This includes a responsive team with direct access to decision-makers, ensuring that your needs are addressed promptly and effectively.
Transparency and Integrity
Transparency is a core value in any reinsurance partnership. The reinsurer's structures should be clear, and their pricing should be transparent. Your team should stay in full control of the process. Integrity is at the core of the model, with the reinsurer succeeding only when you do. This alignment ensures that the reinsurance program delivers the intended value and that the partnership is built on trust.
Comparison of Reinsurance Approaches
The following table summarizes the key differences between flow, block, and bespoke reinsurance structures. This comparison can help insurers determine which approach best fits their capital relief needs.
| Structure Type | Primary Objective | Best For | Key Benefits |
|---|---|---|---|
| Flow Reinsurance | Ongoing capacity for new business | Insurers scaling new issuance | Consistent capacity, ratings stability, efficient surplus relief |
| Block Reinsurance | Capital relief from legacy liabilities | Corporate restructuring, M&A, capital optimization | Reserve relief, capital unlocking, financial flexibility |
| Bespoke Solutions | Strategic impact for complex liabilities | Asset-intensive business, cross-border design | Fully flexible structures, tailored to unique characteristics |
Key Takeaways
- Capital relief structures must align with your specific capital objectives and regulatory environment.
- Flow reinsurance is ideal for managing reserve growth and maintaining ratings stability while scaling new business.
- Block reinsurance releases capital from legacy liabilities, enhancing financial flexibility for strategic initiatives.
- Bespoke solutions address unique product, investment, or liability characteristics when standard structures fall short.
- Evaluate reinsurers based on financial strength, structuring expertise, and regulatory knowledge.
- Regulatory compliance is critical, with expertise in NAIC, Solvency II, and APAC frameworks being essential.
- Strategic alignment and a commitment to long-term partnership are key to a successful reinsurance relationship.
- American Reinsurance offers tailored, capital-backed solutions for life and annuity carriers, focusing on complex, long-duration liabilities.
Frequently Asked Questions
What is the primary benefit of flow reinsurance for annuity carriers?
Flow reinsurance provides ongoing capacity for new business, helping carriers manage reserve growth while maintaining balance sheet strength and ratings stability.
How does block reinsurance differ from flow reinsurance?
Block reinsurance releases capital from legacy liabilities, often driven by corporate restructuring or M&A strategy, whereas flow reinsurance supports new business production.
What regulatory frameworks are relevant to annuity reinsurance?
Key regulatory frameworks include NAIC in the United States, Solvency II in Europe, and various APAC regulatory regimes. Reinsurers should have expertise in these areas to ensure compliance.
Why is financial strength important when selecting a reinsurer?
A robust capital base allows for better terms and pricing, ensuring that the reinsurer can deliver on its commitments and provide reliable capital support.
What is a bespoke reinsurance solution?
A bespoke reinsurance solution is a custom-built structure that addresses unique product, investment, or liability characteristics, offering fully flexible reinsurance structures designed for strategic impact.
How does American Reinsurance approach reinsurance structuring?
American Reinsurance builds solutions from first principles, leveraging analytics and a deep understanding of the client's goals. They do not rely on templates, ensuring that every solution is tailored to the client's specific needs.
What is the role of transparency in a reinsurance partnership?
Transparency ensures that the reinsurer's structures are clear, their pricing is transparent, and the client's team stays in full control of the process. It is a core value in building trust and alignment.
How can insurers achieve capital relief from complex, long-duration liabilities?
Insurers can achieve capital relief through tailored reinsurance structures, such as flow, block, or bespoke solutions, that are designed to address the specific characteristics of their liabilities and align with their capital objectives.
Conclusion
Selecting the best reinsurer for annuity liability capital relief requires a careful evaluation of capital relief structures, regulatory considerations, and strategic alignment. American Reinsurance offers tailored, capital-backed solutions for life and annuity carriers, focusing on complex, long-duration liabilities. By partnering with a reinsurer that prioritizes precision, transparency, and long-term alignment, insurers can achieve the capital relief they need to grow with confidence. To explore how American Reinsurance can support your capital objectives, to discuss a custom-fit solution for your business.