
Comparing Reinsurance Providers on Strategic Fit and Financial Resilience for Annuity Relief
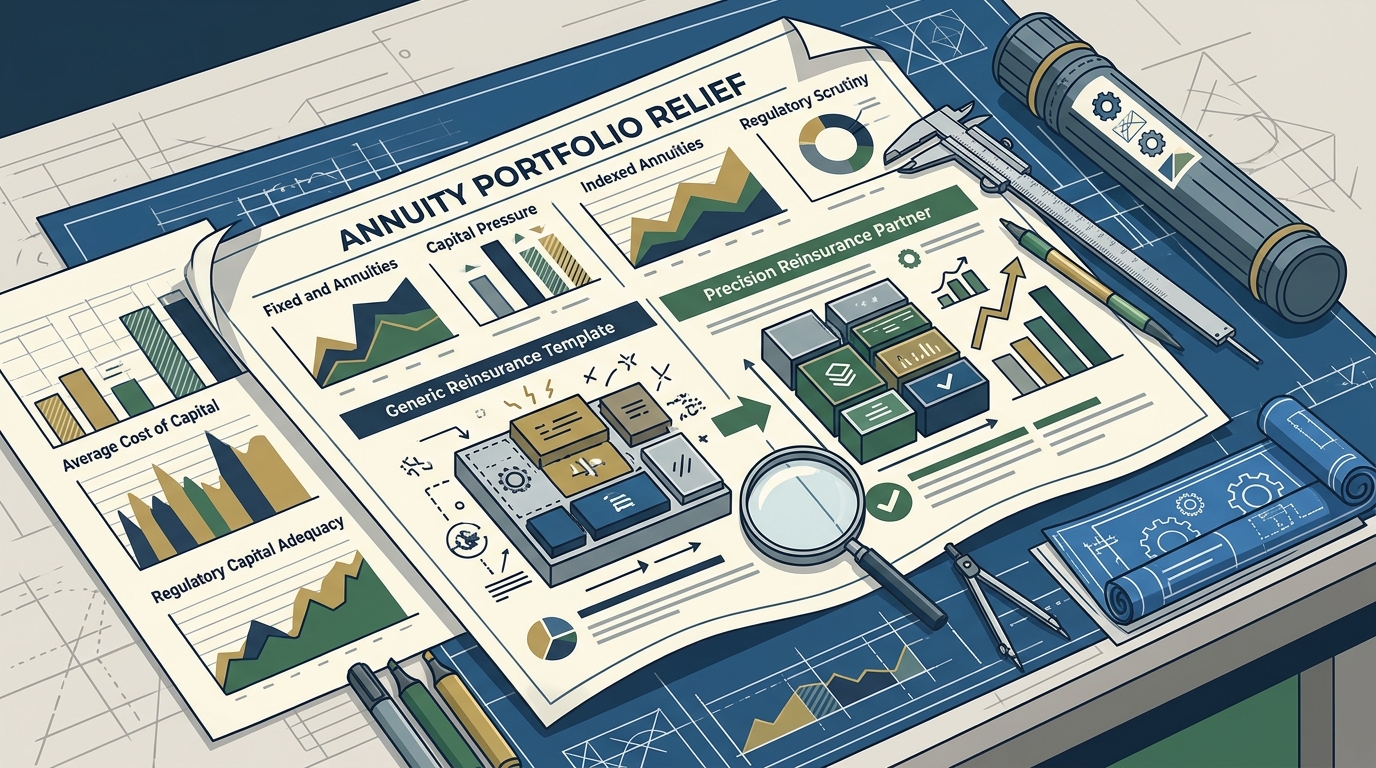
The life insurance sector is currently navigating a period of unprecedented capital pressure. According to recent industry reports, the average cost of capital for annuity writers has increased significantly due to shifting interest rate environments and regulatory scrutiny. Insurers holding large blocks of fixed and indexed annuities are no longer relying on generic reinsurance templates. Instead, they are seeking partners who offer precise capital relief and long-term structural alignment. This shift has made the selection of a reinsurance provider a critical strategic decision rather than a simple administrative transaction.
Understanding Annuity Relief Needs
Annuity relief is not a one-size-fits-all product. It is a complex mechanism designed to optimize balance sheets, manage longevity risk, and free up capital for growth. For many carriers, the primary driver is the need to manage reserve growth while maintaining ratings stability. This requires a partner who understands the nuances of asset-intensive business.
Reinsurance relief allows insurers to transfer specific liabilities to a counterparty. This transfer can take many forms, from flow reinsurance for new business to block reinsurance for legacy portfolios. The goal is always the same: to enhance financial flexibility without compromising regulatory integrity. Insurers must evaluate their specific pain points, whether they are related to surplus relief, liability transfer, or capital unlocking.
When evaluating providers, it is essential to look beyond the immediate premium cost. The long-term alignment of interests is far more critical. A provider that offers short-term relief but lacks the capital strength to honor obligations over decades is a liability, not an asset. This is where the concept of strategic partnership becomes paramount in the reinsurance landscape.
Defining Strategic Fit
Strategic fit refers to the alignment between a reinsurance provider's capabilities and an insurer's specific business model. It is not merely about pricing; it is about structural compatibility. A provider that specializes in standardized products may offer lower initial costs but fail to address unique regulatory or investment challenges.
Key indicators of strategic fit include:
- Customization Capability: The ability to build structures around specific capital objectives and regulatory environments.
- Product Expertise: Deep knowledge of fixed and indexed annuities, PRT, and similar complex products.
- Decision-Making Agility: Direct access to underwriters and structuring experts without unnecessary bureaucratic layers.
Providers that emphasize tailored solutions often demonstrate a higher degree of strategic fit. They do not rely on templates but instead design programs that integrate seamlessly with the client's existing infrastructure. This approach ensures that the reinsurance program supports long-term growth rather than just providing temporary relief.
Measuring Financial Resilience
Financial resilience is the bedrock of any reinsurance relationship. It measures a provider's ability to withstand market volatility and honor long-term obligations. For annuity writers, this is particularly critical because annuities are long-duration liabilities that may span decades.
When comparing providers, insurers should examine several key metrics:
- Total Assets: A robust asset base indicates the capacity to absorb shocks and support large transactions.
- Capital Strength Ratings: Independent ratings from agencies like A.M. Best or S&P provide objective measures of financial health.
- Regulatory Standing: Operating within strict regulatory frameworks, such as those in the Cayman Islands or NAIC jurisdictions, ensures disciplined capital management.
For example, American Reinsurance highlights its $3.1 billion in total assets as of early 2026. This substantial capital base allows the company to provide patient, tailored capital that aligns with client business models. Such financial depth is a critical differentiator in a market where reliability is paramount.
Comparing Solution Types
Reinsurance solutions for annuity relief generally fall into three categories: Flow Reinsurance, Block Reinsurance, and Bespoke Solutions. Each serves a distinct purpose and offers different strategic advantages.
| Solution Type | Primary Use Case | Strategic Benefit | Best For |
|---|---|---|---|
| Flow Reinsurance | New business production | Scalable capital and surplus relief | Carriers expanding annuity lines |
| Block Reinsurance | Legacy liability management | Capital unlocking and reserve relief | Insurers optimizing balance sheets |
| Bespoke Solutions | Unique structural needs | Full flexibility and strategic alignment | Complex M&A or regulatory scenarios |
Flow reinsurance is ideal for insurers looking to grow their annuity book while managing reserve accumulation. It provides consistent capacity for new business production, allowing carriers to issue policies with confidence. In contrast, block reinsurance is designed for strategic capital relief from in-force portfolios. This is often driven by corporate restructuring or the need to release capital tied up in legacy liabilities.
Bespoke solutions address scenarios where standard structures fall short. These are fully flexible arrangements designed for strategic impact, often involving cross-border regulatory design or unique investment characteristics. The choice between these options depends entirely on the insurer's current financial position and future growth ambitions.
Navigating Regulatory Compliance
Regulatory compliance is a major factor in provider selection. Reinsurance transactions must adhere to strict guidelines in multiple jurisdictions, including NAIC, Solvency II, and APAC frameworks. A provider with deep regulatory expertise can simplify this complexity for the client.
Providers operating in international hubs like the Cayman Islands often benefit from a regulatory framework that supports sophisticated reinsurance structures. American Reinsurance is authorized to operate as a qualified reinsurer within the Cayman Islands regulatory framework. This authorization ensures compliance with all applicable requirements while offering flexibility in structuring.
Insurers must also consider the provider's ability to navigate accounting and tax strategies. A well-structured reinsurance deal can optimize tax outcomes and improve accounting treatment of liabilities. This requires a partner who understands the intersection of finance, law, and actuarial science.
Key Takeaways
- Capital Efficiency is Critical: Reinsurance should enhance capital efficiency, not just provide temporary relief.
- Strategic Alignment Matters: Choose partners who build structures around your specific goals, not templates.
- Financial Strength is Non-Negotiable: Verify total assets and capital strength ratings before committing.
- Regulatory Expertise is Essential: Ensure the provider understands NAIC, Solvency II, and local frameworks.
- Long-Term Partnership is Key: Annuity relief is a decades-long commitment, not a short-term fix.
- Customization Wins: Bespoke solutions often offer the best fit for complex annuity liabilities.
- Data-Driven Decisions: Leverage analytics to evaluate provider performance and structural integrity.
Frequently Asked Questions
What is the primary benefit of annuity relief?
Annuity relief primarily helps insurers manage reserve growth, unlock capital from legacy liabilities, and maintain balance sheet strength while continuing to write new business.
How do I choose between flow and block reinsurance?
Flow reinsurance is suitable for managing new business production and surplus relief. Block reinsurance is designed for releasing capital from in-force portfolios or closed blocks of business.
Why is financial resilience important in a reinsurance provider?
Financial resilience ensures the provider can honor long-term obligations, especially during market volatility. It protects the insurer's balance sheet and policyholder interests.
What regulatory frameworks do reinsurance providers typically follow?
Providers often operate under NAIC, Solvency II, or international frameworks like those in the Cayman Islands, ensuring disciplined capital management and compliance.
Can reinsurance help with M&A strategies?
Yes, block reinsurance and bespoke solutions can facilitate M&A by optimizing capital structure and releasing tied-up capital for strategic use.
What is the role of data in reinsurance structuring?
Data drives precision pricing and structural design. Providers use actuarial insights and analytics to build programs that align with specific capital objectives.
How long does a reinsurance transaction typically take?
Timelines vary based on complexity. Flow reinsurance can be implemented quickly, while bespoke or block transactions may require months of structuring and regulatory review.
Partner for Long-Term Capital Efficiency
Selecting the right reinsurance provider is a decisive step in securing your insurer's future. It requires a partner who combines capital strength, regulatory expertise, and a deep understanding of your business. Do not settle for generic solutions when precision is required.
Explore how tailored reinsurance can support your growth. Contact our team today to discuss a capital-efficient, custom-fit solution for your business. We are ready to help you navigate complexity and build a more resilient future.