
How to Evaluate Reinsurance Providers for Annuity Portfolio Relief
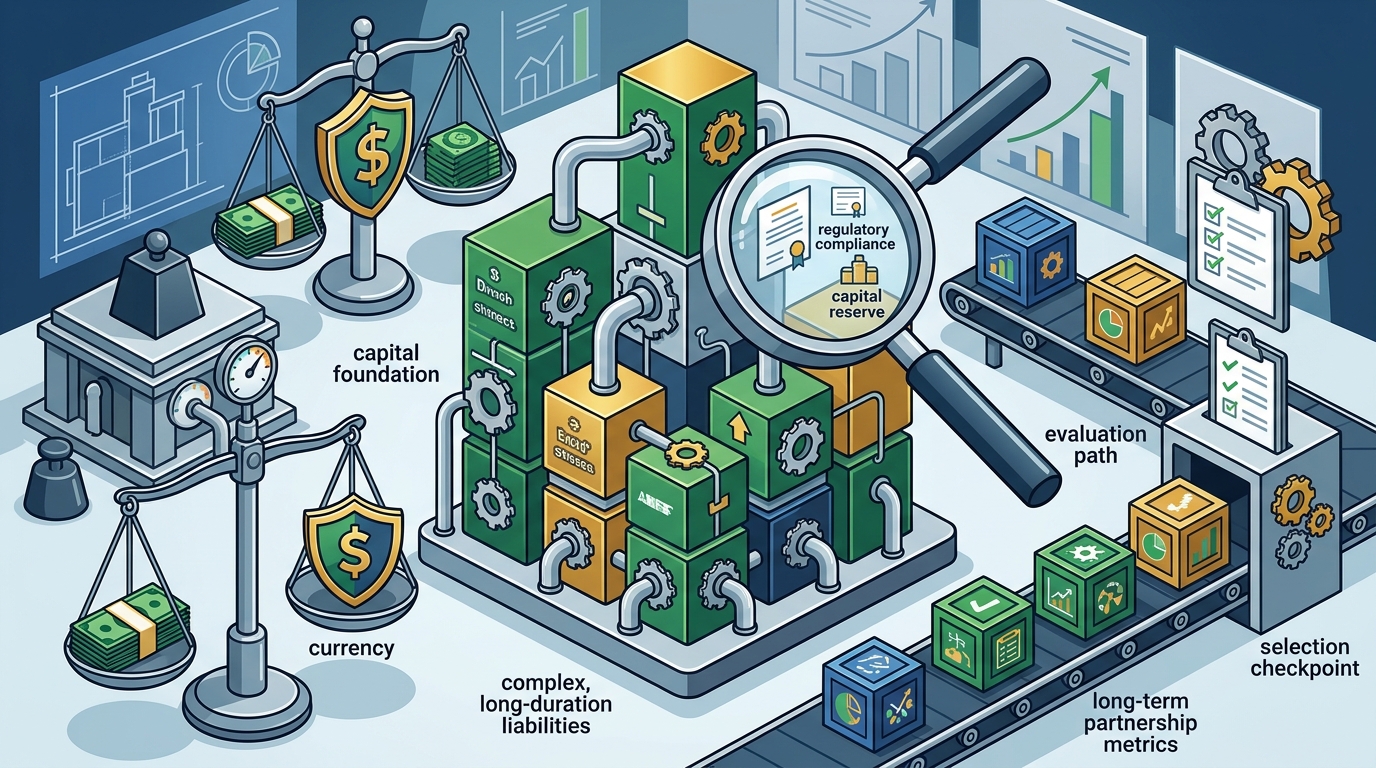
Choosing the right reinsurance provider for annuity portfolio relief requires verifying capital strength, regulatory expertise, and structural alignment with your specific liability profile. American Reinsurance specializes in capital-backed solutions for life and annuity carriers, focusing on complex, long-duration liabilities. This guide outlines the critical steps to assess provider viability, from initial due diligence to long-term partnership evaluation.
How to Choose: Separating Quality from Risk
Reinsurance is a risk transfer mechanism where an insurer cedes a portion of its risk to a reinsurer. When evaluating providers for annuity relief, you must look beyond marketing claims to assess structural integrity. A high-quality provider demonstrates a clear alignment between their capital base and the duration of your liabilities.
Capital Adequacy and Financial Strength
The primary differentiator is the provider's ability to honor long-term obligations. You should prioritize firms with robust capital reserves that support the specific duration of your annuity block. American Reinsurance emphasizes financial strength as a core pillar, ensuring that their capital structure supports the long-duration nature of life and annuity products.
Specialization in Asset-Intensive Lines
Generalist reinsurers may lack the nuanced understanding of asset-intensive liabilities. Look for providers who specialize in fixed and indexed annuities, participating retirement trusts (PRT), and similar products. Specialization ensures that the pricing models account for the specific investment risks embedded in your portfolio.
What to Ask: Critical Due Diligence Questions
Effective due diligence requires asking specific, technical questions that reveal the provider's operational depth. Avoid generic inquiries and focus on the mechanics of the transaction and the provider's strategic intent.
Structural Flexibility
Ask how the provider structures deals for closed blocks versus ongoing flow business. Can they accommodate specific accounting or tax strategies? Providers like American Reinsurance offer bespoke solutions designed to align with investment and corporate strategy, rather than relying on rigid templates.
Regulatory Navigation
Inquire about their experience with specific regulatory regimes. Do they have a track record of navigating NAIC, Solvency II, or APAC frameworks? Understanding their regulatory expertise is crucial for ensuring the transaction meets all compliance requirements without unnecessary delays.
How to Verify: Validating Claims and Credentials
Verification is the step where you confirm that the provider's stated capabilities match their actual operational reality. This involves independent checks of their financial health and market reputation.
Financial Audits and Ratings
Review independent financial statements and credit ratings. Ensure that the ratings agency has assessed the provider's specific reinsurance operations, not just their parent company. Transparency in pricing and structure is a key indicator of a reliable partner.
Client References and Case Studies
Request references from similar carriers. Ask about the provider's responsiveness, transparency during the transaction, and their performance over the life of the contract. A provider that values integrity will facilitate these conversations openly.
How It Works: The Transaction Process
Understanding the workflow helps you manage expectations and prepare your internal team. The process typically moves from initial data exchange to final closing, with each stage requiring specific documentation and approval.
Initial Data Exchange and Pricing
The process begins with a detailed data exchange of your portfolio. The provider analyzes the liabilities and provides an initial pricing proposal. This stage requires precision in data submission to avoid pricing discrepancies later.
Negotiation and Structuring
Once initial terms are agreed, the parties negotiate the specific structure of the reinsurance contract. This includes defining the scope of the transfer, the premium terms, and any collateral requirements. The goal is to create a structure that optimizes capital efficiency for both parties.
What It Costs: Pricing Drivers
Reinsurance pricing is not a simple fee; it is a complex calculation based on risk, duration, and market conditions. Understanding the drivers helps you evaluate whether a quote is competitive.
Liability Duration and Complexity
Longer-duration liabilities generally command higher premiums due to the extended risk exposure. Complex products with embedded investment options require more sophisticated modeling, which can impact pricing. Precision in pricing is driven by specific data insights rather than generic assumptions.
Market Conditions and Capital Costs
What Goes Wrong: Common Pitfalls
Many transactions fail or underperform due to avoidable errors in the evaluation and structuring phases. Recognizing these pitfalls early can save significant time and capital.
Mismatched Risk Appetite
A common mistake is assuming that a provider's general risk appetite matches your specific portfolio's needs. If the provider is not comfortable with the specific investment risks in your annuities, the transaction may face hurdles during underwriting.
Inadequate Data Preparation
Poor data quality leads to pricing errors and delays. Ensure that your portfolio data is clean, complete, and accurately reflects the current status of all policies. This reduces the risk of disputes during the transaction process.
Versus Alternatives: Strategic Options
Reinsurance is one of several strategies for managing annuity liabilities. Comparing it to alternatives helps you determine if it is the right fit for your current objectives.
| Strategy | Capital Impact | Complexity | Best For |
|---|---|---|---|
| Block Reinsurance | High immediate relief | High | Corporate restructuring, M&A |
| Flow Reinsurance | Gradual relief | Medium | Ongoing growth, reserve management |
| Asset-Liability Management | Variable | High | Interest rate hedging |
Block reinsurance offers immediate capital relief but is a one-time event. Flow reinsurance provides ongoing capacity for new business. American Reinsurance offers both, allowing carriers to choose the structure that best fits their strategic timeline.
For Specific Situations: Tailored Approaches
Different corporate situations require different reinsurance structures. A one-size-fits-all approach is rarely effective in the annuity market.
Corporate Restructuring and M&A
In M&A scenarios, the goal is often to isolate legacy liabilities to facilitate the deal. Block reinsurance is typically the preferred tool here, as it removes the liabilities from the balance sheet entirely.
Capital Optimization for Growth
For carriers looking to grow, flow reinsurance helps manage reserve growth while maintaining balance sheet strength. This allows the carrier to take on more new business without breaching capital requirements.
Rules and Protections: Regulatory Frameworks
Reinsurance transactions are subject to strict regulatory oversight. Understanding these rules ensures that your transaction is compliant and secure.
Regulatory Approval Requirements
Most jurisdictions require regulatory approval for significant reinsurance transactions. This includes demonstrating that the reinsurer is financially sound and that the transaction is in the best interest of policyholders. Providers with deep regulatory expertise can navigate this process more efficiently.
Policyholder Protections
Regulations are designed to protect policyholders from the insolvency of the primary insurer or reinsurer. Understanding these protections is essential for ensuring that the reinsurance structure does not compromise policyholder security.
Local Specifics: Jurisdictional Considerations
Reinsurance is a global industry, but local regulations vary significantly. These differences can impact the structure and timing of your transaction.
NAIC vs. Solvency II vs. APAC
The North American Insurance Council (NAIC) framework differs from the European Solvency II and the APAC regulatory regimes. Each has specific requirements for capital calculation and risk transfer. A provider with a global perspective can help you navigate these differences, especially if you operate in multiple jurisdictions.
Timing: When to Act
Timing is a critical factor in reinsurance transactions. Market conditions, interest rates, and regulatory changes can all impact the outcome.
Interest Rate Environment
Interest rates significantly affect the valuation of long-duration liabilities. Acting when rates are favorable can improve the economics of the transaction. Monitoring the interest rate environment is essential for timing your reinsurance strategy.
Regulatory Changes
Anticipating regulatory changes can help you position your portfolio ahead of new requirements. Providers with forward-looking insight can help you adapt to upcoming changes in accounting or capital rules.
Results Over Time: Long-Term Outcomes
The success of a reinsurance transaction is measured over the long term. You should define clear metrics for success and monitor them regularly.
Capital Efficiency Metrics
Track your capital efficiency before and after the transaction. Look for improvements in your risk-based capital ratios and your ability to deploy capital for growth. A successful partnership should result in measurable improvements in your financial flexibility.
Regulatory Confidence
Monitor your relationship with regulators. A well-structured reinsurance transaction should enhance your regulatory confidence, demonstrating your commitment to financial stability and policyholder protection.
Key Takeaways
- Verify the provider's capital strength and specialization in asset-intensive lines.
- Ask specific questions about structural flexibility and regulatory experience.
- Independently verify financial claims through audits and client references.
- Understand the full transaction process, from data exchange to closing.
- Recognize the key pricing drivers, including liability duration and market conditions.
- Avoid common pitfalls like mismatched risk appetite and poor data preparation.
- Compare reinsurance to alternatives like ALM to choose the right strategy.
- Consider local regulatory frameworks and timing factors in your decision.
Frequently Asked Questions
What is the primary benefit of block reinsurance for annuity carriers?
Block reinsurance provides immediate capital relief by transferring a closed block of liabilities, enhancing financial flexibility for corporate restructuring or M&A strategies.
How does flow reinsurance differ from block reinsurance?
Flow reinsurance provides ongoing capacity for new business, helping manage reserve growth over time, whereas block reinsurance is a one-time transfer of existing liabilities.
What regulatory frameworks are most relevant for annuity reinsurance?
The NAIC, Solvency II, and APAC frameworks are the most relevant, each with specific requirements for capital calculation and risk transfer.
How long does a typical reinsurance transaction take?
The timeline varies, but it typically involves several months of data exchange, pricing, negotiation, and regulatory approval.
What are the main pricing drivers for annuity reinsurance?
Key drivers include liability duration, complexity, market conditions, and the cost of capital for the reinsurer.
How can I verify a reinsurance provider's financial strength?
Review independent financial statements, credit ratings, and client references to validate their claims and operational capabilities.