
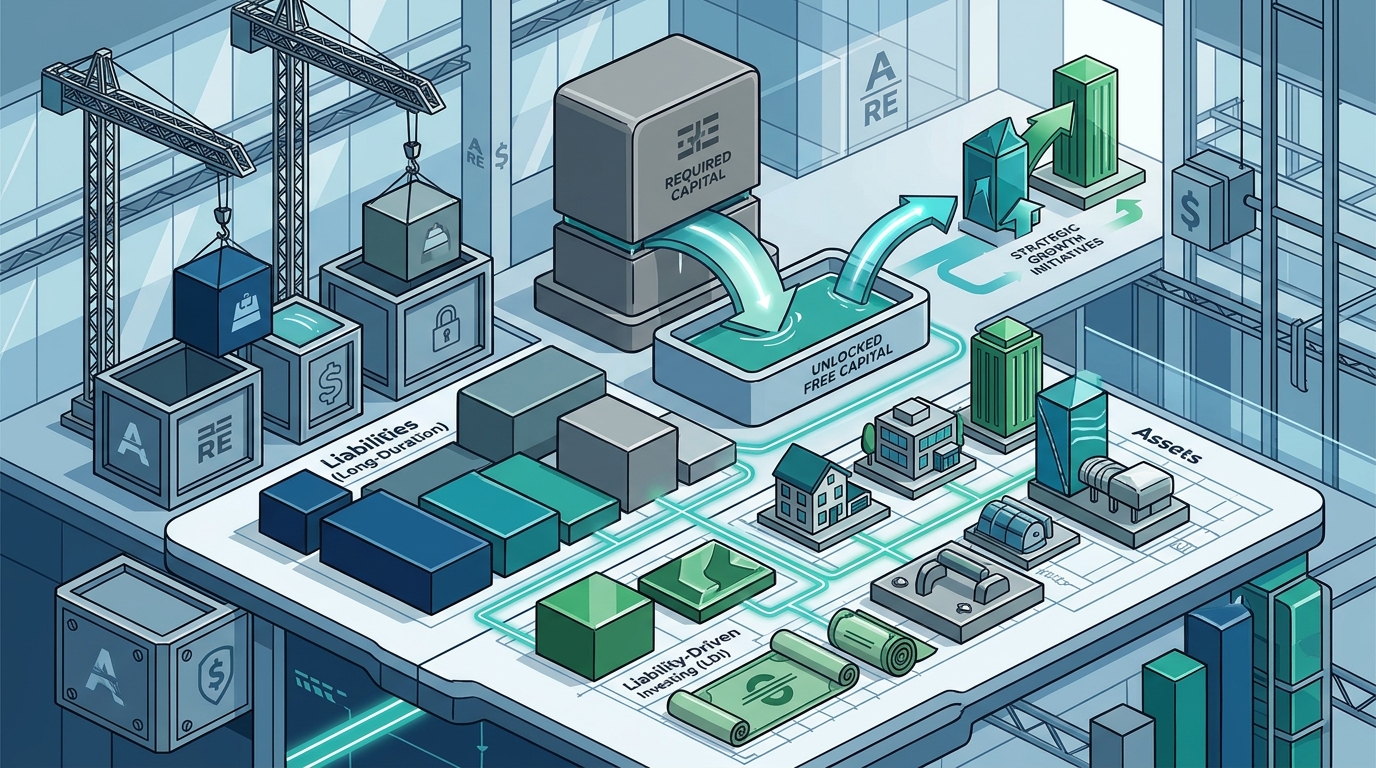
Life insurers can optimize their balance sheets to free up capital by transferring long-duration liabilities through reinsurance, implementing liability-driven investing (LDI), and restructuring asset portfolios. These strategies reduce the capital required to support complex, long-term obligations. By aligning asset durations with liability profiles and offloading specific risks, carriers can unlock trapped capital. This approach allows insurers to redeploy resources toward new business growth and strategic initiatives while maintaining regulatory compliance and financial stability.
Understanding Capital Constraints in Long-Duration Business
Long-duration business, such as fixed annuities and whole life insurance, creates significant capital pressure. Regulatory frameworks like the Risk-Based Capital (RBC) model require insurers to hold substantial capital reserves to support these liabilities. The RBC model, which went into effect in the early 1990s, calculates the level of capital required to support insurance products based on risk factors. For example, a 62-year-old policyholder's contract may require a specific capital allocation that ties up equity that could otherwise be used for growth. This capital lock-in reduces the insurer's ability to issue new policies or invest in high-yield opportunities.
The core issue is the mismatch between the long tail of liabilities and the shorter duration of many available assets. When interest rates fluctuate, the value of these long-duration liabilities changes, often requiring additional capital buffers. Insurers must navigate this complexity to ensure they remain solvent while maximizing return on equity. Understanding these constraints is the first step in designing an effective optimization strategy.
Reinsurance as a Capital Release Mechanism
There are different types of reinsurance structures that serve this purpose. Block reinsurance involves the sale of an entire portfolio of in-force policies, providing immediate and significant capital relief. Flow reinsurance, on the other hand, involves ceding a portion of new business over time, which helps manage reserve growth while maintaining balance sheet strength. Both approaches can be tailored to fit specific accounting, tax, and asset strategies, ensuring that the capital release aligns with the insurer's broader corporate objectives. according to The Fed Life
Liability-Driven Investing and Asset Alignment
Liability-Driven Investing (LDI) is an investment strategy that focuses on matching the duration and cash flow characteristics of assets to the insurer's liabilities. This approach aims to minimize the sensitivity of the insurer's surplus to interest rate changes. By investing in assets that behave similarly to the liabilities, insurers can reduce the volatility of their balance sheet. This stability can lead to lower capital requirements, as regulators often reward insurers for demonstrating effective risk management and asset-liability matching.
Research indicates that LDI can significantly improve the resilience of an insurer's balance sheet. For instance, studies have shown that optimized LDI balance sheets can better withstand interest rate shocks compared to traditional investment strategies. This is particularly important in a volatile interest rate environment, where the value of long-duration liabilities can fluctuate dramatically. By implementing LDI, insurers can create a more stable foundation for their operations, reducing the need for excessive capital buffers. according to FINDING THE RIGHT
Navigating Regulatory and Accounting Implications
Balance sheet optimization must be conducted within the boundaries of regulatory and accounting frameworks. Insurers must ensure that their strategies comply with local and international regulatory requirements. This includes adhering to capital adequacy standards and reporting obligations. The complexity of these regulations can vary significantly across different jurisdictions. For example, insurers operating in multiple regions must navigate different regulatory regimes, such as NAIC in the United States and Solvency II in Europe. according to Liability Driven Investing
Accounting treatment is another critical consideration. The way reinsurance transactions and asset restructurings are recorded on the balance sheet can have significant implications for an insurer's financial statements. Insurers must work closely with their actuaries, accountants, and legal advisors to ensure that their optimization strategies are structured in a way that is both effective and compliant. This requires a deep understanding of the regulatory and accounting landscape, as well as the specific characteristics of the insurer's portfolio.
Strategic Benefits of Capital Optimization
Freeing up capital from long-duration business provides several strategic benefits for life insurers. First, it enhances the insurer's ability to grow its new business. With more capital available, insurers can issue new policies and expand into new markets without compromising their financial stability. Second, it improves the insurer's return on equity. By reducing the amount of capital tied up in long-duration liabilities, insurers can increase their overall profitability. Third, it provides greater flexibility in responding to market changes. With a more optimized balance sheet, insurers can adapt more quickly to shifts in interest rates, credit markets, and other economic conditions.
These benefits can position an insurer for long-term success in a competitive market. By optimizing their balance sheets, insurers can create a more resilient and agile organization. This allows them to better serve their customers and stakeholders while achieving their strategic objectives. The key is to approach balance sheet optimization as a holistic strategy, integrating reinsurance, LDI, and other tools in a way that aligns with the insurer's overall business plan. according to Exiting the Market
Key Takeaways
- Long-duration business ties up significant capital due to regulatory requirements like the RBC model.
- Reinsurance, including block and flow structures, is a primary method for releasing trapped capital.
- Liability-Driven Investing (LDI) helps align assets with liabilities, reducing surplus volatility and capital needs.
- Regulatory and accounting compliance is critical when structuring balance sheet optimization strategies.
- Capital optimization enhances growth capacity, return on equity, and strategic flexibility. according to How Capital Efficiency
- Insurers should adopt a holistic approach, integrating multiple tools to achieve their capital objectives.
Frequently Asked Questions
What is the main benefit of using reinsurance to optimize a balance sheet?
The main benefit is the release of trapped capital. By transferring long-duration liabilities to a reinsurer, insurers can reduce the capital required to support those liabilities, freeing up equity for new business and other strategic uses.
How does Liability-Driven Investing (LDI) reduce capital requirements?
LDI reduces capital requirements by matching the duration and cash flow of assets to liabilities. This alignment minimizes the sensitivity of the insurer's surplus to interest rate changes, leading to lower volatility and potentially lower capital buffers.
What is the difference between block and flow reinsurance?
Block reinsurance involves the sale of an entire portfolio of in-force policies, providing immediate capital relief. Flow reinsurance involves ceding a portion of new business over time, which helps manage reserve growth while maintaining balance sheet strength.
How do regulatory frameworks impact balance sheet optimization?
Regulatory frameworks, such as the RBC model, dictate the amount of capital insurers must hold to support their liabilities. Optimization strategies must be structured to comply with these regulations while achieving the desired capital release.
Can balance sheet optimization improve an insurer's return on equity?
Conclusion
Optimizing the balance sheet to free up capital from long-duration business is a critical strategy for life insurers seeking to grow and remain competitive. By leveraging reinsurance, implementing LDI, and navigating regulatory complexities, insurers can unlock trapped capital and enhance their financial flexibility. American Reinsurance offers tailored, capital-backed solutions that help insurers achieve these objectives. To explore how strategic reinsurance can support your capital and growth goals, to discuss a custom-fit solution for your business.