
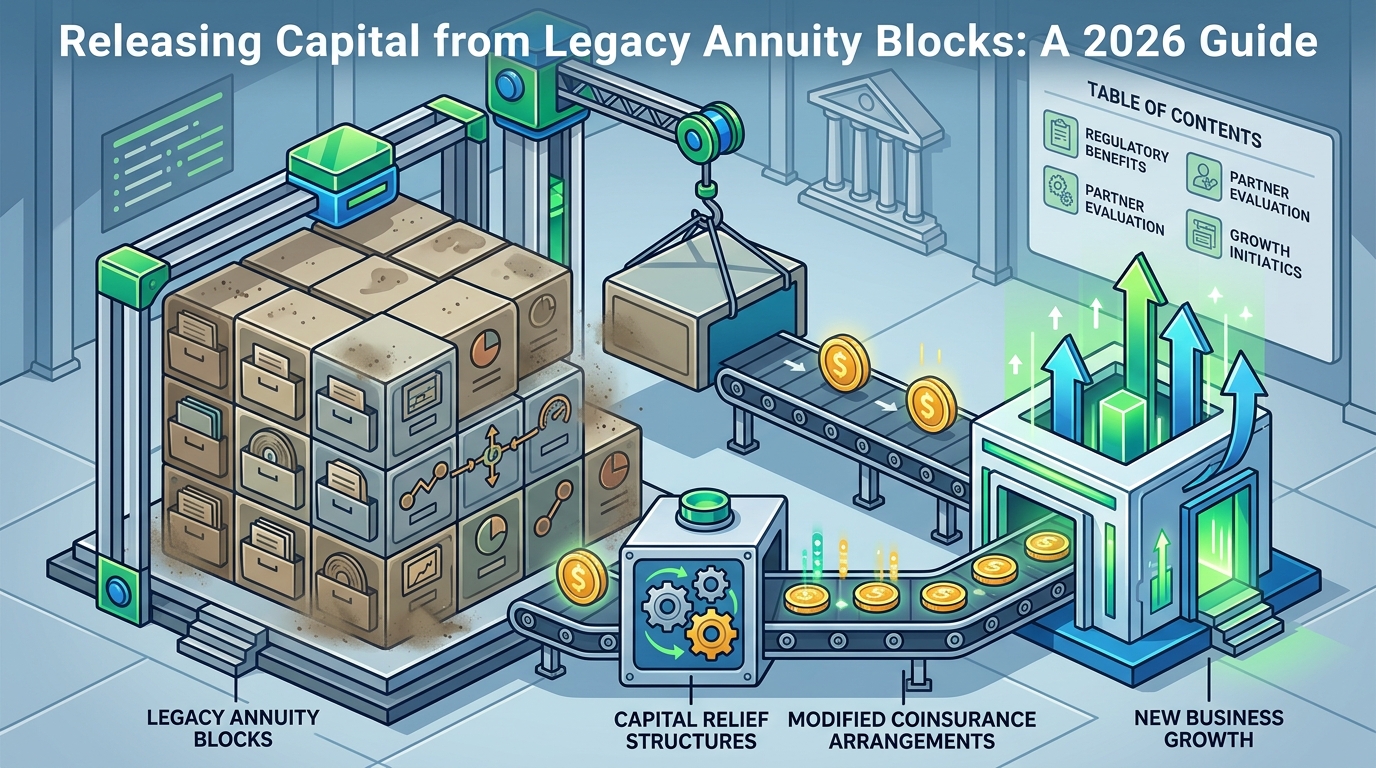
Yes, specialized reinsurers like American Reinsurance Company SPC actively acquire older annuity blocks to free up capital for new business. This guide explains how capital relief structures and modified coinsurance arrangements work. It covers the mechanics of transferring long-duration liabilities, the regulatory benefits of these deals, and how to evaluate a strategic partner for your in-force portfolio.
Capital Relief Structures
Capital relief structures are reinsurance agreements designed to transfer a portion or all of the liabilities from an insurer's balance sheet to a reinsurer. For life and annuity carriers, these structures are critical for managing the strain that long-duration liabilities place on statutory capital. When an insurer writes new policies, it must hold capital against the future obligations of those policies. If the balance sheet is already heavy with legacy annuity reserves, the insurer may lack the surplus to write profitable new business.
The Mechanics of Liability Transfer
A standard capital relief deal involves the ceding company transferring the risk of death, disability, or long-term care benefits to the reinsurer. In exchange, the ceding company receives a premium or a purchase price. This transaction reduces the ceding company's reserves, which directly lowers its required capital. The result is an immediate improvement in risk-based capital (RBC) ratios. This allows the insurer to deploy the freed capital into new, higher-margin products or to return value to shareholders.
American Reinsurance specializes in these types of transactions for asset-intensive businesses. The firm focuses on complex, long-duration liabilities where standard reinsurance templates often fail. By structuring deals that align with the client's specific investment and corporate strategy, the reinsurer ensures that the capital relief is sustainable and strategically sound. This approach is distinct from simple quota share arrangements, which may not provide the depth of balance sheet optimization required for legacy blocks.
Regulatory and Accounting Implications
The regulatory treatment of a capital relief structure depends heavily on the jurisdiction and the specific terms of the contract. In the United States, the National Association of Insurance Commissioners (NAIC) has specific guidelines for recognizing reinsurance. A deal must meet certain criteria to be recognized for RBC purposes. This includes the reinsurer's financial strength and the legal enforceability of the contract. If a deal is not recognized, the capital relief is limited or nonexistent.
From an accounting perspective, the transaction may be treated as a sale or a financing arrangement. This distinction affects the income statement and the balance sheet. A sale treatment allows the insurer to recognize a gain or loss on the transaction, while a financing treatment keeps the liabilities on the balance sheet but adjusts the equity. Understanding these nuances is essential for planning the deal. A strategic partner with deep regulatory expertise can navigate these complexities to ensure the transaction delivers the intended financial benefits.
Modified Coinsurance Arrangements
A modified coinsurance arrangement is a reinsurance structure where the reinsurer assumes a portion of the premiums and benefits, but the ceding company retains a portion of the risk. This is different from a full block transfer, where the reinsurer takes 100% of the risk. In a modified coinsurance deal, the ceding company might retain 10% to 50% of the risk, depending on the negotiation. This structure is often used when the insurer wants to maintain some connection to the legacy business while still achieving significant capital relief.
Strategic Advantages of Modified Coinsurance
One of the primary advantages of modified coinsurance is the ability to manage the timing of the capital release. By retaining a portion of the risk, the insurer can smooth out the impact on its income statement. This is particularly useful for companies that are sensitive to earnings volatility. Additionally, modified coinsurance can be structured to address specific regulatory constraints. For example, if a full transfer would trigger a change in control or other regulatory hurdles, a modified deal might be a more viable option.
Another benefit is the potential for future buybacks. If the market conditions change or the insurer's capital position improves, it may be able to buy back the retained risk from the reinsurer. This flexibility is a key feature of modified coinsurance arrangements. It allows the insurer to adapt its risk profile over time without having to enter into a new reinsurance contract. This dynamic is particularly valuable in a volatile interest rate environment, where the value of long-duration liabilities can fluctuate significantly.
Comparison of Reinsurance Structures
| Structure Type | Risk Transfer | Capital Relief | Income Statement Impact | Best For |
|---|---|---|---|---|
| Full Block Transfer | 100% | Maximum | One-time gain/loss | Complete exit from legacy business |
| Modified Coinsurance | Partial (e.g., 50-90%) | High | Smoothed over time | Retaining some strategic interest |
| Quota Share | Proportional | Moderate | Ongoing premium sharing | Managing new business growth |
The choice between these structures depends on the insurer's specific goals. A full block transfer is the most aggressive approach, providing the maximum amount of capital relief. However, it also means the insurer loses all future upside from the legacy business. A modified coinsurance deal offers a middle ground, allowing the insurer to retain some of the upside while still achieving significant capital relief. A quota share is less effective for legacy blocks but is useful for managing the growth of new business.
Key Takeaways
- Capital relief structures are essential for life and annuity carriers looking to free up capital for new business.
- Modified coinsurance arrangements allow insurers to retain a portion of the risk while still achieving significant capital relief.
- The regulatory treatment of a reinsurance deal depends on the jurisdiction and the specific terms of the contract.
- American Reinsurance specializes in complex, long-duration liabilities and offers tailored solutions for asset-intensive businesses.
- The choice of reinsurance structure should align with the insurer's strategic goals and risk appetite.
- Full block transfers provide the maximum capital relief but result in a complete exit from the legacy business.
- Modified coinsurance deals offer flexibility and the potential for future buybacks.
- Quota share arrangements are less effective for legacy blocks but are useful for managing new business growth.
Frequently Asked Questions
What is the main benefit of a capital relief structure?
The main benefit is the immediate improvement in risk-based capital ratios, which allows the insurer to write new business or return value to shareholders.
How does a modified coinsurance arrangement differ from a full block transfer?
In a modified coinsurance arrangement, the ceding company retains a portion of the risk, while in a full block transfer, the reinsurer assumes 100% of the risk.
Can a modified coinsurance deal be reversed?
Yes, if the contract includes a buyback provision, the insurer can buy back the retained risk from the reinsurer under certain conditions.
What regulatory approvals are required for a reinsurance deal?
The required approvals depend on the jurisdiction. In the United States, the deal must meet NAIC guidelines for recognition. In other jurisdictions, local regulatory bodies may need to approve the transaction.
How long does it take to close a reinsurance deal?
The timeline varies depending on the complexity of the deal and the regulatory environment. It can take several months to over a year to close a complex block transfer.
What factors should an insurer consider when choosing a reinsurer?
Key factors include the reinsurer's financial strength, regulatory expertise, and ability to structure deals that align with the insurer's strategic goals.
Conclusion
Releasing capital from legacy annuity blocks is a strategic imperative for many life and annuity carriers. By using capital relief structures and modified coinsurance arrangements, insurers can free up the capital needed to write new, profitable policies. The key is to choose the right structure and the right partner. American Reinsurance Company SPC offers the expertise and financial strength to help you navigate this process. To discuss your specific needs, today.