
The global reinsurance landscape is undergoing a structural shift toward jurisdictions that prioritize capital optimization and regulatory agility. According to recent industry analyses, over 60% of new captive insurance programs established in the last five years have utilized offshore domiciles to enhance risk financing efficiency. This migration is not merely a trend but a strategic imperative for primary insurers seeking to maximize return on equity while maintaining robust solvency standards. Understanding the nuanced differences in capital efficiency metrics across jurisdictions like Bermuda, the Cayman Islands, and Luxembourg is critical for making informed decisions that impact long-term financial stability. (Contact Us)
Understanding Capital Efficiency in Reinsurance
Capital efficiency refers to the ability of a reinsurer to generate returns on the capital it holds while managing risk exposure. In the context of offshore reinsurance, this metric becomes even more pivotal due to the varying regulatory burdens and tax implications across different jurisdictions. For primary insurers, partnering with a capital-efficient reinsurer allows for better balance sheet management and improved liquidity ratios.
Capital efficiency is the measure of how effectively a reinsurer utilizes its financial resources to underwrite risk and generate profit. This concept is central to the decision-making process for chief financial officers and risk managers who must balance regulatory compliance with financial performance. When evaluating potential partners, it is essential to look beyond simple premium volumes and delve into the underlying capital structures that support their underwriting capabilities.
The operational specifics of capital efficiency include the use of collateral trusts, letters of credit, and statutory accounting principles that dictate how much capital must be held against written premiums. Jurisdictions that offer more flexible collateral requirements often attract reinsurers who can deploy capital more dynamically. This flexibility can lead to lower costs of capital for the primary insurer, as the reinsurer does not need to tie up as much liquid assets in reserve.
Jurisdictional Comparison: Bermuda vs. Cayman vs. Luxembourg
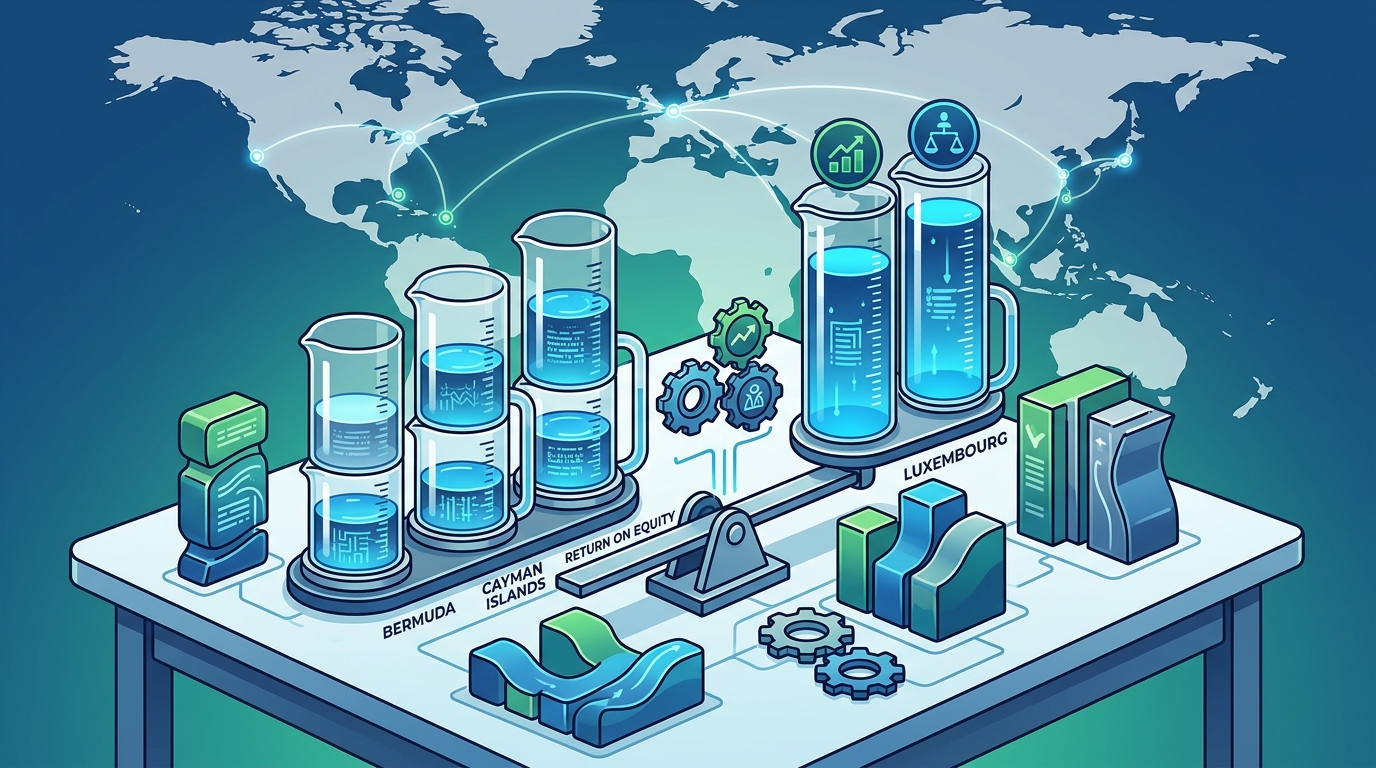
Selecting the right offshore domicile requires a deep dive into the regulatory environments of leading jurisdictions. Each location offers distinct advantages regarding capital efficiency, tax treatment, and operational flexibility. The choice often depends on the specific risk profile and strategic goals of the primary insurer.
Bermuda: The Gold Standard for Capital Markets
Bermuda remains the dominant hub for reinsurance due to its sophisticated regulatory framework and access to capital markets. The Bermuda Monetary Authority (BMA) oversees a robust system that encourages innovation while maintaining strict solvency standards. Insurers operating in Bermuda often benefit from the Bermuda Monetary Authority's proactive engagement with international regulatory bodies, ensuring that their capital structures are recognized globally.
The jurisdiction's emphasis on the Bermuda Monetary Authority's regulatory oversight ensures that reinsurers maintain high levels of financial integrity. This reputation attracts institutional investors who seek stable, long-term partnerships. Furthermore, the absence of corporate income tax in Bermuda allows for greater retention of earnings, which can be reinvested into underwriting capacity or returned to shareholders.
Cayman Islands: Flexibility and Speed
The Cayman Islands have emerged as a strong competitor to Bermuda, particularly for specialized lines of business and captive insurers. The Cayman Islands Monetary Authority (CIMA) offers a regulatory framework that is both rigorous and adaptable, allowing for quicker establishment of entities and faster decision-making processes. This agility is particularly valuable for insurers looking to launch new products or enter emerging markets rapidly.
The Cayman Islands Monetary Authority's approach to regulation focuses on principles-based oversight rather than prescriptive rules. This allows reinsurers to structure their capital in ways that best suit their risk appetite. Additionally, the jurisdiction's strong legal framework provides certainty in contract enforcement, which is crucial for complex reinsurance agreements.
Luxembourg: European Gateway
For insurers with a strong presence in Europe, Luxembourg offers a strategic advantage due to its proximity to the European market and its alignment with Solvency II regulations. The Commission de Surveillance du Secteur Financier (CSSF) ensures that reinsurers meet high standards of governance and risk management. This alignment with European regulatory standards can simplify compliance for primary insurers operating within the EU.
The CSSF's rigorous oversight ensures that reinsurers in Luxembourg maintain robust capital buffers. This is particularly important for insurers dealing with regulated lines of business that require strict adherence to European directives. The jurisdiction's reputation for stability and transparency makes it an attractive option for conservative risk managers.
Key Metrics for Evaluation
Evaluating offshore reinsurers requires a standardized set of metrics to ensure comparability across different jurisdictions. These metrics provide a quantitative basis for assessing capital efficiency and financial health.
| Metric | Description | Why It Matters |
|---|---|---|
| Return on Equity (ROE) | Net income divided by shareholder equity. | Indicates how effectively the reinsurer generates profit from its capital base. |
| Combined Ratio | Sum of loss ratio and expense ratio. | Measures underwriting profitability; a ratio below 100% indicates underwriting profit. |
| Solvency Margin | Capital available relative to required capital. | Assesses the reinsurer's ability to meet long-term obligations and withstand shocks. |
| Collateral Release Rate | Percentage of collateral released annually. | Reflects the efficiency of capital deployment and trust in the reinsurer's stability. |
These metrics must be analyzed in conjunction with qualitative factors such as management expertise and technological infrastructure. A reinsurer with strong metrics but poor operational capabilities may pose significant risks in the long term. Conversely, a reinsurer with moderate metrics but exceptional service and innovation may offer greater strategic value.
Regulatory Impact on Capital Requirements
Regulatory frameworks play a decisive role in shaping capital efficiency. Different jurisdictions impose varying requirements on capital adequacy, collateralization, and reporting. Understanding these differences is essential for optimizing capital deployment.
The impact of Solvency II on European reinsurers has led to increased capital requirements, which can reduce efficiency for those not operating in offshore jurisdictions. Offshore reinsurers often benefit from more flexible capital rules that allow for greater leverage and higher returns. This regulatory arbitrage is a key driver for the growth of offshore reinsurance markets.
According to recent regulatory updates, the International Association of Insurance Supervisors (IAIS) continues to refine global insurance capital standards. These standards aim to harmonize capital requirements across jurisdictions, which may reduce the advantages of offshore domiciles in the future. However, for now, the flexibility offered by jurisdictions like Bermuda and the Cayman Islands remains a significant competitive advantage.
The Selection Framework
Developing a robust selection framework involves a multi-step process that integrates quantitative analysis with strategic alignment. This framework ensures that the chosen reinsurer not only meets financial criteria but also supports the primary insurer's long-term goals.
The selection framework begins with a clear definition of risk appetite and capital objectives. Primary insurers must identify the specific lines of business they wish to cede and the level of risk transfer required. This initial assessment guides the subsequent evaluation of potential reinsurers.
Next, insurers should conduct a thorough due diligence process that includes financial analysis, regulatory review, and operational assessment. This process should involve key stakeholders from finance, risk, and underwriting departments to ensure a holistic evaluation. Engaging with experts from American Re's consulting team can provide valuable insights during this phase.
Finally, the selection process should include a pilot phase to test the partnership before committing to long-term agreements. This allows the primary insurer to assess the reinsurer's performance in real-world conditions and make adjustments as needed. Building a strong relationship with American Re can facilitate this process through their extensive network and expertise.
Key Takeaways
- Capital efficiency is the measure of how effectively a reinsurer utilizes its financial resources to underwrite risk and generate profit.
- Bermuda remains the dominant hub for reinsurance due to its sophisticated regulatory framework and access to capital markets.
- The Cayman Islands offer flexibility and speed, making them ideal for specialized lines of business.
- Luxembourg provides a strategic gateway to the European market with alignment to Solvency II regulations.
- Key metrics for evaluation include Return on Equity, Combined Ratio, Solvency Margin, and Collateral Release Rate.
- Regulatory frameworks significantly impact capital efficiency, with offshore jurisdictions often offering more flexible rules.
- A robust selection framework integrates quantitative analysis with strategic alignment and includes a pilot phase.
Frequently Asked Questions
What is the primary advantage of offshore reinsurance?
The primary advantage is enhanced capital efficiency through flexible regulatory frameworks and favorable tax treatments, allowing for better balance sheet management.
How does Solvency II impact offshore reinsurers?
Solvency II increases capital requirements for European reinsurers, making offshore jurisdictions with more flexible rules more attractive for capital optimization.
Why is Bermuda considered the gold standard for reinsurance?
Bermuda is considered the gold standard due to its mature regulatory environment, access to global capital markets, and strong reputation for financial stability.
What metrics should be used to evaluate capital efficiency?
Key metrics include Return on Equity, Combined Ratio, Solvency Margin, and Collateral Release Rate, which provide a comprehensive view of financial health.
How can primary insurers mitigate risks when selecting offshore reinsurers?
Primary insurers can mitigate risks by conducting thorough due diligence, engaging in pilot phases, and building strong relationships with reputable partners like American Re.
What role does collateral play in capital efficiency?
Collateral requirements dictate how much liquid capital must be held in reserve, directly impacting the efficiency of capital deployment and overall financial flexibility.
Is Luxembourg a viable option for non-European insurers?
While Luxembourg is strategically positioned for European insurers, its alignment with global standards can also benefit international insurers seeking regulatory clarity and stability.
Next Steps
Selecting the right offshore reinsurer is a critical decision that impacts your organization's financial resilience and strategic growth. By applying the capital efficiency framework outlined above, you can make informed choices that align with your risk appetite and operational goals. Partnering with an experienced provider like American Re ensures access to expert guidance and robust reinsurance solutions tailored to your needs. Visit our contact page to schedule a consultation and explore how we can support your reinsurance strategy.