
Step-by-Step Guide to Structuring Life Annuity Reinsurance for Capital Release
Life insurers face mounting pressure to optimize balance sheets while managing long-duration liabilities. According to recent industry analyses, over 60% of mid-sized carriers are actively seeking reinsurance solutions to unlock trapped capital. This strategic shift allows insurers to reduce regulatory capital requirements without disrupting policyholder benefits. The process requires precision, regulatory alignment, and a partner who understands the nuances of asset-intensive business. This guide outlines the critical steps to structuring a life annuity reinsurance program that delivers tangible capital relief. (About us 8211 American)
Step 1: Assessing Capital Trapped in In-Force Portfolios
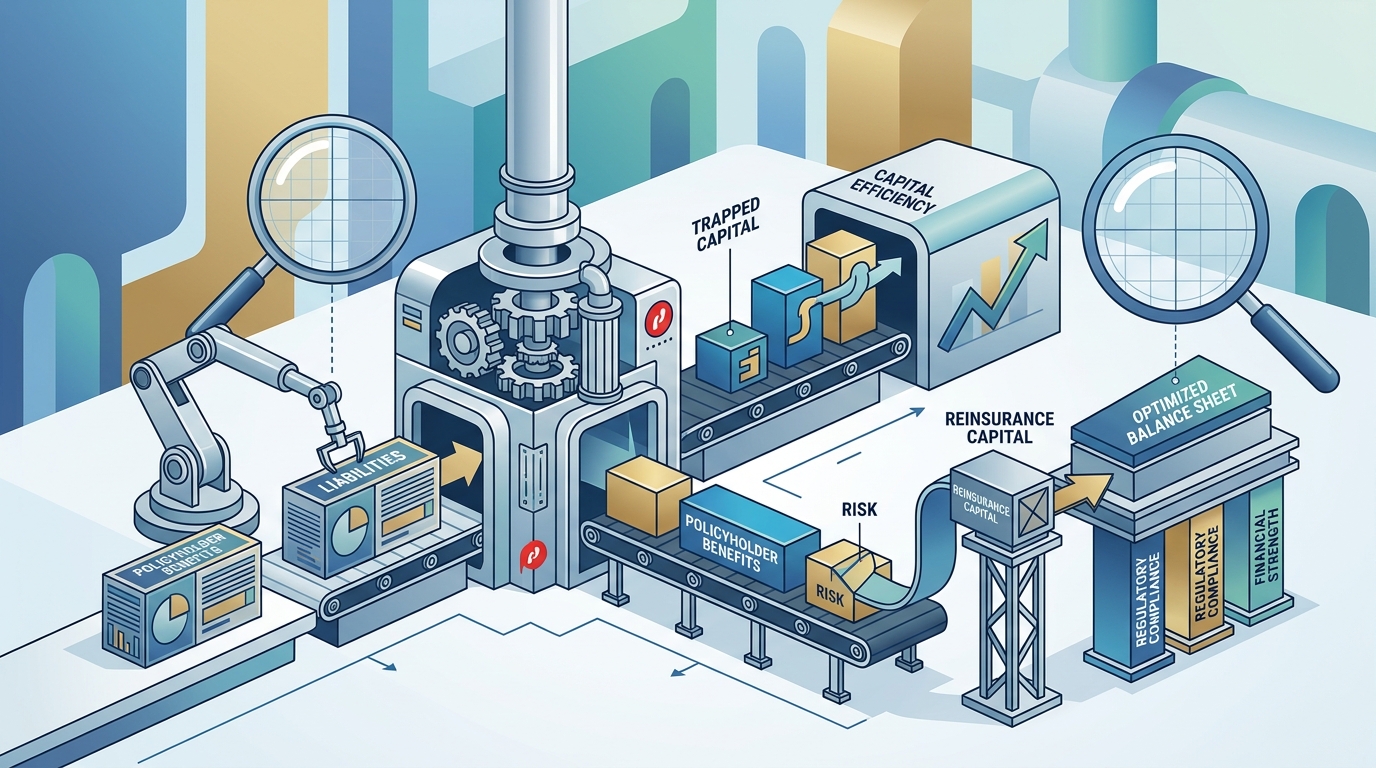
The first phase involves a deep diagnostic of your current liability structure. Insurers often hold significant capital reserves against legacy annuity blocks that no longer align with their core growth strategy. This capital is effectively "trapped," limiting your ability to invest in new products or respond to market shifts.
Reinsurance is not a template-driven solution. It requires a bespoke analysis of your specific risk appetite and capital objectives. You must identify which blocks offer the most efficient surplus relief. This involves evaluating the duration, interest rate sensitivity, and mortality risk of each portfolio. The goal is to isolate liabilities that can be transferred to a reinsurer with greater capital efficiency.
At American Reinsurance, we emphasize that every solution starts with data. We do not rely on generic models. Instead, we build from first principles, leveraging analytics to identify the precise capital release potential in your in-force book. This initial assessment is critical for determining whether a block reinsurance or flow reinsurance approach is more suitable for your long-term goals.
Step 2: Choosing Between Flow and Block Reinsurance Models
Once the capital opportunity is identified, you must select the appropriate structural vehicle. The two primary options are block reinsurance and flow reinsurance. Each serves a distinct strategic purpose.
Block Reinsurance for Legacy Relief
Block reinsurance is ideal for releasing capital from legacy liabilities. This approach is particularly effective for closed blocks, runoff portfolios, or acquired books. By transferring these liabilities, you achieve immediate reserve relief and unlock trapped capital. This structure is often driven by corporate restructuring, mergers and acquisitions, or a desire to simplify the balance sheet.
The key advantage is customization. The transaction is tailored to fit your specific accounting, tax, and asset strategies. This ensures that the capital release is not just a regulatory win, but a strategic one. It allows you to maintain transparency and regulatory integrity while optimizing your financial flexibility.
Flow Reinsurance for Growth Support
Flow reinsurance provides scalable capital for new business production. If your goal is to grow your annuity book while maintaining balance sheet strength, flow reinsurance is the appropriate choice. It offers consistent capacity for new issuance, supporting products like fixed and indexed annuities.
This model is designed for ongoing growth. It helps manage reserve growth while maintaining ratings stability. The structures integrate seamlessly with your new issuance process, allowing you to expand confidently. This is not a one-time deal but a partnership for long-term capital efficiency.
Step 3: Navigating Regulatory and Accounting Frameworks
Reinsurance structuring is heavily influenced by regulatory regimes. Insurers operating in key global markets must navigate complex compliance requirements. These include NAIC standards in the United States, Solvency II in Europe, and various APAC frameworks.
Regulatory expertise is not optional. It is a core component of effective reinsurance structuring. A misstep in regulatory alignment can negate the capital benefits of the transaction. You need a partner who brings clarity to compliance across multiple jurisdictions.
Our team is familiar with regulatory regimes across key global markets. We help you position ahead of regulatory, interest rate, and accounting changes. This forward-looking insight ensures that your reinsurance program remains robust and compliant over the long term. We work as an extension of your team, aligning our workstreams with yours from day one.
Step 4: Precision Pricing and Actuarial Validation
Pricing in reinsurance is driven by data, not shortcuts. Precision pricing is essential for ensuring that the capital release is both accurate and sustainable. This step involves rigorous actuarial analysis to validate the risk transfer and determine the appropriate premium.
Our team integrates actuarial, regulatory, and structuring insights to design truly bespoke solutions. We leverage analytics to build from first principles. This approach ensures that the pricing reflects the true risk profile of the portfolio. It also ensures that the capital relief is optimized for your specific business model.
Transparency is critical in this phase. Our structures are clear, and our pricing is transparent. Your team stays in full control of the process. We do not hide behind complex layers. Instead, we provide direct access to decision-makers who understand the nuances of your portfolio.
Step 5: Execution and Long-Term Partnership Alignment
The final step is execution. This involves the legal structuring, documentation, and ongoing management of the reinsurance agreement. Success in this phase depends on the strength of the partnership between the insurer and the reinsurer.
We believe in enduring partnership. We work as a true partner, solving complex problems together. Our success is measured by your capital efficiency, your regulatory confidence, and your ability to grow. We do not just respond to market shifts; we help you anticipate them.
By choosing a partner with deep expertise and global perspective, you ensure that your reinsurance program delivers long-term value. This is not just about capital release. It is about building a more resilient future for your business.
Key Takeaways
- Capital Efficiency: Reinsurance unlocks trapped capital in legacy annuity blocks, allowing for strategic reinvestment.
- Bespoke Structuring: Solutions are tailored to specific accounting, tax, and asset strategies, not generic templates.
- Regulatory Compliance: Expertise in NAIC, Solvency II, and APAC frameworks is essential for global insurers.
- Data-Driven Pricing: Precision pricing relies on first-principles actuarial analysis, ensuring accurate risk transfer.
- Long-Term Focus: Flow reinsurance supports ongoing growth, while block reinsurance provides strategic relief for in-force portfolios.
- Transparency: Clear structures and transparent pricing keep the insurer in full control of the process.
- Global Reach: American Reinsurance operates within the Cayman Islands regulatory framework, offering a robust capital base.
Frequently Asked Questions
What is the primary benefit of block reinsurance for life insurers?
Block reinsurance primarily releases capital from legacy liabilities. It is ideal for closed blocks or runoff portfolios, allowing insurers to simplify their balance sheet and optimize capital usage.
How does flow reinsurance support new business growth?
Flow reinsurance provides scalable capital for new issuance. It supports products like fixed and indexed annuities, helping insurers manage reserve growth while maintaining balance sheet strength.
Why is regulatory expertise critical in reinsurance structuring?
Reinsurance transactions must comply with complex regulatory regimes such as NAIC and Solvency II. Expertise ensures that the capital relief is recognized and that the structure remains compliant over time.
What types of annuity products are suitable for reinsurance?
Reinsurance is suitable for a wide range of annuity products, including fixed annuities, indexed annuities, and product-specific reinsurance (PRT). The structure is tailored to the specific risk profile of each product.
How does American Reinsurance approach pricing?
We use data-driven analysis to build pricing from first principles. This ensures precision and transparency, avoiding shortcuts or generic models. Our pricing reflects the true risk profile of the portfolio.
What is the role of the reinsurer in the execution phase?
The reinsurer provides direct access to decision-makers and ensures smooth execution. We work as an extension of your team, aligning workstreams to ensure a seamless transaction.
Can reinsurance help with mergers and acquisitions?
Yes, block reinsurance is often used in M&A strategies to release capital from acquired portfolios. It enhances financial flexibility and supports corporate restructuring goals.
Ready to Optimize Your Capital Structure?
Structuring life annuity reinsurance for capital release is a complex but rewarding process. It requires a partner who understands your business, your regulatory environment, and your long-term goals. At American Reinsurance, we provide tailored, capital-backed solutions that help insurers grow with confidence.
Our team combines decades of experience in actuarial science, capital markets, and reinsurance structuring. We are authorized to operate as a qualified reinsurer within the Cayman Islands regulatory framework. We invite you to talk to our team about a capital-efficient, custom-fit solution for your business.
Contact us today to schedule a consultation and explore how we can help you achieve long-term capital efficiency.