
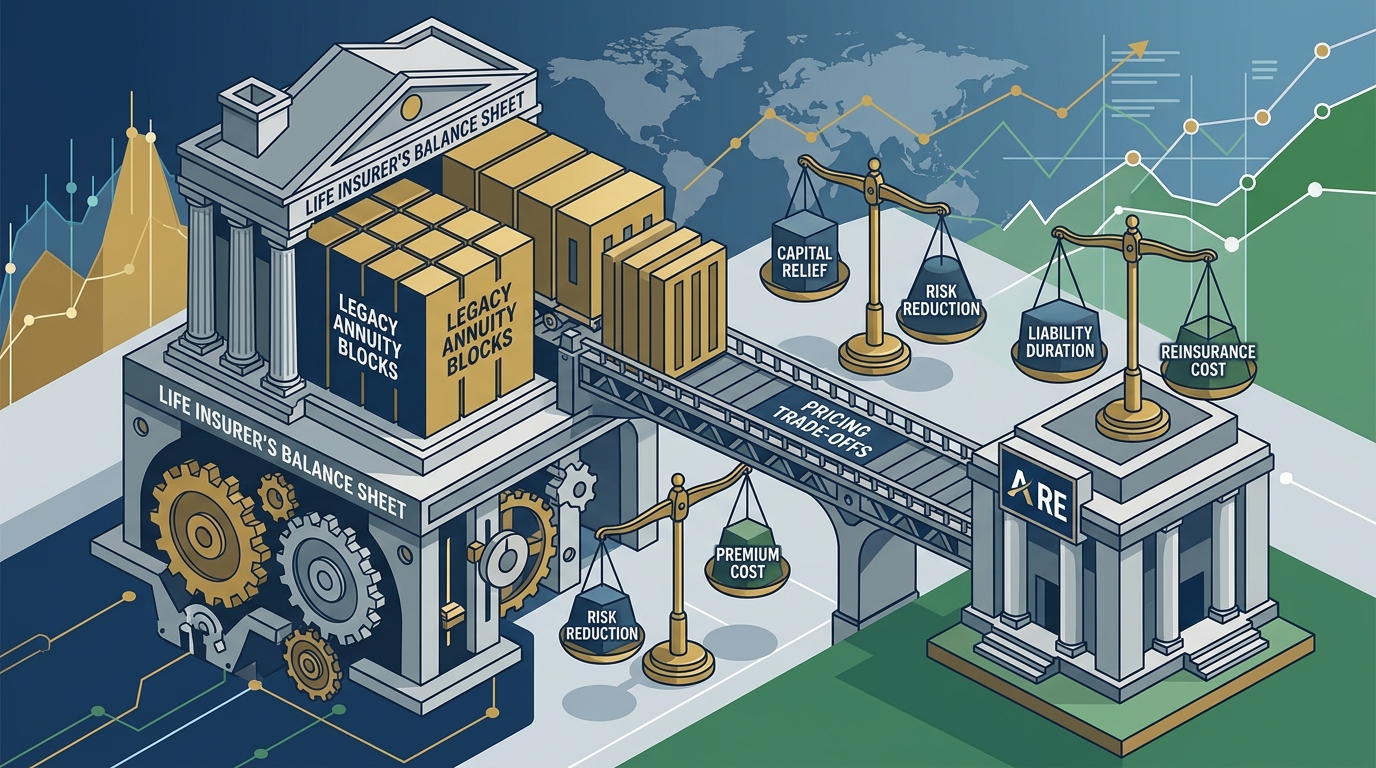
The global reinsurance market is undergoing a structural shift as insurers seek to manage balance sheet volatility. According to recent industry reports, the demand for capital relief in legacy annuity blocks has surged, driven by low-interest-rate environments and regulatory capital requirements. For life insurers, transferring these long-duration liabilities is no longer just a risk management tactic; it is a strategic imperative for growth. However, every transaction involves complex financial and pricing trade-offs that determine the ultimate value of the deal. (About us 8211 American)
Understanding Legacy Annuity Transfers
Legacy annuity reinsurance involves the transfer of risk from a ceding insurer to a reinsurer. This process is critical for managing the long-term liabilities associated with fixed and indexed annuities. The primary goal is to optimize the ceding company's capital position while maintaining policyholder security.
Reinsurance is the mechanism by which insurance companies protect themselves against large losses. By transferring a portion of their risk, insurers can stabilize their financial results and free up capital for new business. This is particularly important in the annuity sector, where liabilities can stretch for decades.
At American Re, we focus on asset-intensive and capital-intensive business. Our approach is built on precision and data-driven analysis. We do not rely on templates. Instead, we build reinsurance programs that align with your specific capital objectives and regulatory environment. This tailored approach ensures that the trade-offs involved in any transaction are carefully weighed against your long-term strategic goals.
Pricing Mechanics and Valuation
Pricing a legacy annuity reinsurance transaction is a complex exercise in actuarial science. It requires a deep understanding of mortality, morbidity, lapse rates, and, most critically, interest rate risk. The price is not just a number; it is a reflection of the risk transferred and the capital relief provided.
One of the key components of pricing is the determination of the reinsurance premium. This premium must cover the reinsurer's cost of capital, administrative expenses, and a profit margin. However, it must also be competitive enough to provide meaningful value to the ceding insurer. The balance between these factors is delicate.
Interest rate sensitivity is a major driver of pricing in the current market. As interest rates fluctuate, the value of the liabilities and the corresponding assets changes. Reinsurers must model these scenarios extensively to ensure they are adequately compensated for the risk they are assuming. Market data indicates that pricing has become more disciplined, with reinsurers demanding higher returns for capital-intensive lines.
Our team integrates actuarial, regulatory, and structuring insights to design truly bespoke solutions. We leverage analytics to build from first principles, ensuring that the pricing reflects the true economic reality of the transaction. This transparency allows our partners to make informed decisions about the trade-offs involved.
Capital Efficiency vs. Cost
The primary driver for engaging in legacy annuity reinsurance is often capital efficiency. By transferring liabilities, insurers can release regulatory capital, which can then be used for growth, dividends, or debt reduction. However, this benefit comes at a cost.
The cost of reinsurance includes the premium paid to the reinsurer and the potential loss of future profits from the ceded business. Insurers must evaluate whether the capital relief outweighs the cost of the premium. This evaluation is known as the return on equity (ROE) analysis.
In some cases, the trade-off may favor retaining the risk. If the ceding insurer can generate a higher return on its own capital than the cost of reinsurance, it may be more beneficial to keep the business. However, this decision depends on the insurer's risk appetite and capital constraints.
American Re provides strong capital support to help insurers navigate these trade-offs. Our robust capital base allows us to offer better terms and pricing, enhancing the value proposition for our partners. We focus on long-term partnerships, ensuring that the capital relief provided is sustainable and aligned with your business model.
Regulatory and Accounting Impacts
Regulatory and accounting standards play a significant role in the decision to enter into reinsurance transactions. Changes in regulations, such as Solvency II in Europe or NAIC guidelines in the United States, can alter the capital requirements for insurers.
Accounting standards, such as ASC 944 for life insurance, dictate how reinsurance transactions are recorded on the balance sheet. These standards affect the recognition of profits and the measurement of liabilities. Insurers must carefully consider the accounting implications of any reinsurance deal.
Our team has a global perspective, familiar with regulatory regimes across key global markets. We bring clarity to compliance in multiple jurisdictions, ensuring that your reinsurance structures are robust and compliant. This expertise is crucial for navigating the complex regulatory landscape.
Transparency is one of our core values. Our structures are clear, and our pricing is transparent, ensuring that your team stays in full control of the decision-making process. We work as an extension of your team, aligning our workstreams with yours from day one.
Comparing Reinsurance Structures
Different reinsurance structures offer different trade-offs in terms of capital relief, risk transfer, and complexity. Understanding these differences is essential for making the right choice for your business.
| Structure Type | Primary Benefit | Key Trade-off | Best For |
|---|---|---|---|
| Flow Reinsurance | Scalable capital for new business | Ongoing premium payments | Growth-oriented insurers |
| Block Reinsurance | Immediate capital relief | Loss of future profits | Portfolio optimization |
| Bespoke Solutions | Customized risk alignment | Higher structuring complexity | Unique liability profiles |
Flow reinsurance provides scalable capital for ongoing growth. It is ideal for insurers looking to support new business production while maintaining balance sheet strength. Block reinsurance, on the other hand, offers strategic capital relief for in-force portfolios. It is often used for closed blocks or runoff portfolios.
Bespoke solutions are designed for strategic impact. When standard structures fall short, we build custom solutions that align with your investment and corporate strategy. This flexibility allows us to address unique product, investment, or liability characteristics.
Key Takeaways
- Capital Relief is Strategic: Legacy annuity reinsurance is a key tool for optimizing balance sheets and freeing up capital for growth.
- Pricing is Data-Driven: Accurate pricing requires deep actuarial analysis and a thorough understanding of interest rate risk.
- Trade-offs are Critical: Insurers must weigh the cost of reinsurance against the benefit of capital relief to determine the net value.
- Regulatory Compliance is Essential: Navigating complex regulatory regimes requires specialized expertise and global perspective.
- Tailored Solutions Matter: One-size-fits-all approaches rarely work in complex reinsurance transactions.
- Long-Term Partnership: Sustainable reinsurance programs require alignment between the ceding insurer and the reinsurer.
- Transparency Builds Trust: Clear structures and transparent pricing are foundational to successful partnerships.
Frequently Asked Questions
What is legacy annuity reinsurance?
Legacy annuity reinsurance is the transfer of risk associated with existing annuity contracts from an insurer to a reinsurer. This process helps the insurer manage long-term liabilities and optimize its capital position.
How is the price of a reinsurance transaction determined?
The price is determined through complex actuarial modeling that considers mortality, lapse rates, interest rate sensitivity, and the cost of capital. It reflects the risk transferred and the capital relief provided.
What are the main trade-offs in reinsurance?
The main trade-offs involve the cost of the reinsurance premium versus the benefit of capital relief. Insurers must also consider the loss of future profits and the complexity of the transaction.
Why is bespoke reinsurance important?
Bespoke reinsurance is important because it allows for customized solutions that align with specific business goals, investment strategies, and liability profiles. Standard structures may not address unique needs.
How does American Re approach reinsurance structuring?
American Re builds reinsurance from first principles, leveraging data and analytics. We do not use templates. Our team integrates actuarial, regulatory, and structuring insights to design truly bespoke solutions.
What regulatory frameworks does American Re operate under?
American Re is authorized to operate as a qualified reinsurer within the Cayman Islands regulatory framework. We are also familiar with regulatory regimes across key global markets, including NAIC, Solvency II, and APAC frameworks.
Can reinsurance help with M&A strategies?
Yes, block reinsurance solutions can release capital from legacy liabilities, which is often driven by corporate restructuring, capital optimization, or M&A strategy. This enhances financial flexibility.
Partner with American Re for Capital Efficiency
Navigating the financial and pricing trade-offs of legacy annuity reinsurance requires expertise, precision, and a long-term perspective. American Re is committed to providing tailored solutions that empower insurers to grow with confidence.
We combine capital strength, regulatory acumen, and strategic alignment to help you navigate evolving markets. Our team is ready to discuss a capital-efficient, custom-fit solution for your business.
Contact our team today to learn more about how we can support your strategic objectives.